Pressure Broadens Beyond Gasoline as the Core Trend Rises Again
October’s headline rose 0.4% against consensus of 0.3%, and the increase was broad, with shelter accounting for more than 30% of it. Core prices rose 0.3% against a consensus of 0.2%, the third straight 0.3%, and core services outside housing ran about 0.39% after 0.34% in September. The threshold we laid out in July still holds, and the Committee, which held on October 28 with two dissents in favor of a hike, has more work to do, as we expected.
Early Signals
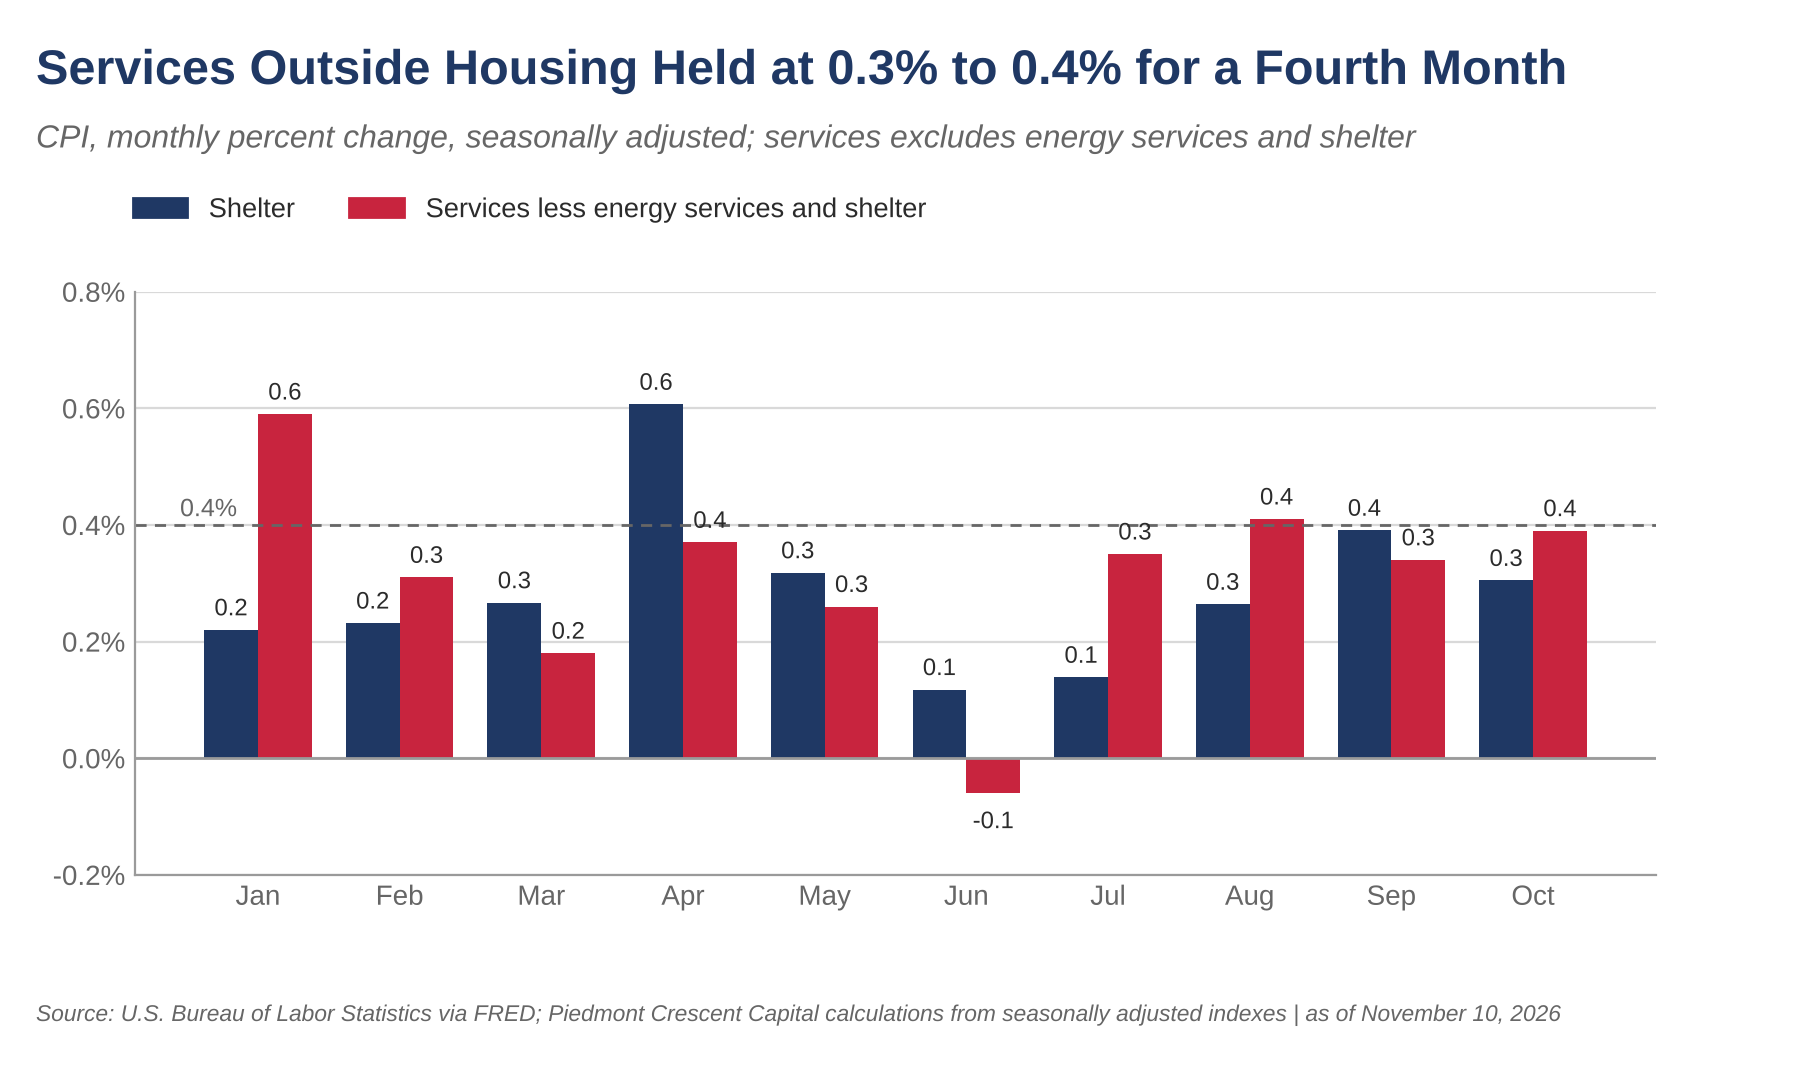
- The threshold we laid out in July still holds. Core services outside housing (services less energy services and shelter, our calculation from the BLS seasonally adjusted indexes) rose 0.41% in August, 0.34% in September and about 0.39% in October, a three-month average of 0.38%. Shelter rose 0.3% in October after 0.4% in September and 0.3% in August, a step back from September’s pace.
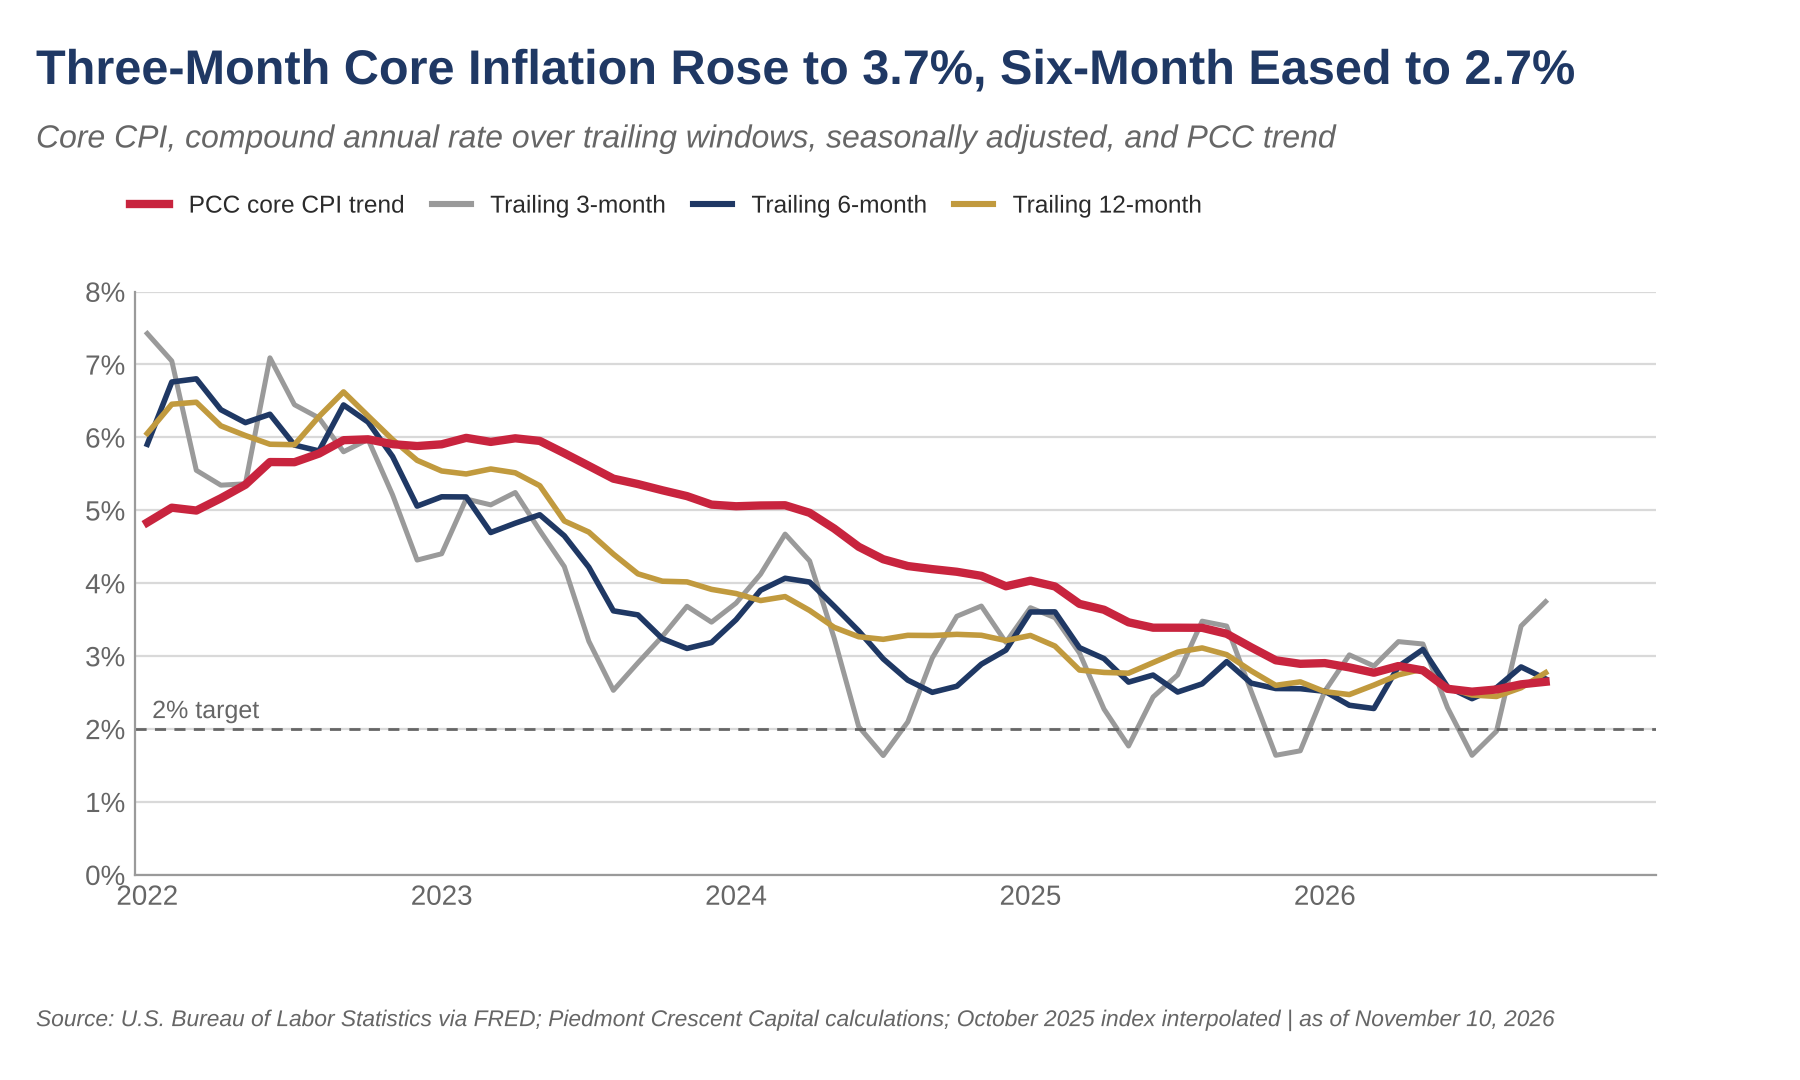
- The underlying trend rose for a third straight month. Our one-sided HP-filter estimate of trend core inflation rose to 2.65% in October from 2.61% in September. It is still well below the 3.12% reading from a year ago, but core CPI has compounded at a 3.7% annual rate over the past three months, up from 3.4% in September.
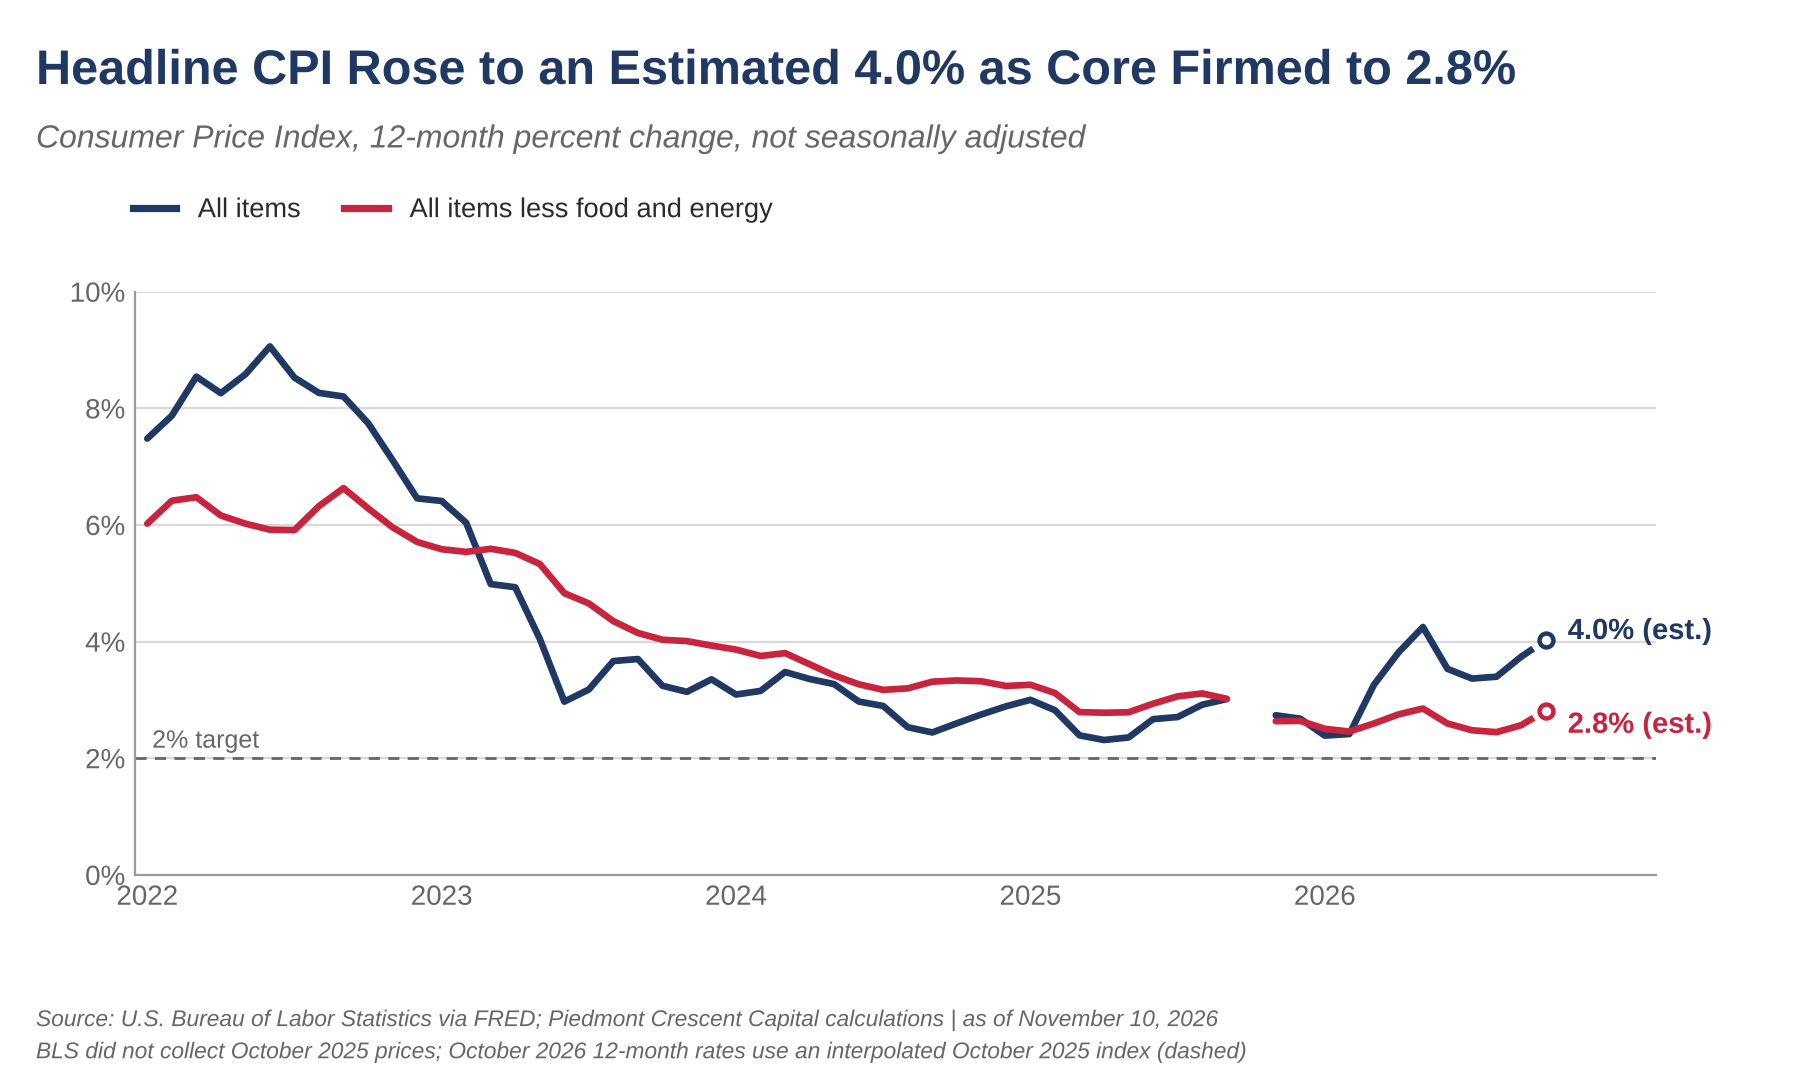
- Inflation pressure broadened beyond gasoline. The all items index rose 0.4%, a tenth above consensus. Shelter accounted for more than 30% of the increase, food rose 0.5% and energy rose 0.7%, with gasoline up 1.0% seasonally adjusted but down 0.7% before adjustment. BLS did not collect October 2025 prices during the shutdown and publishes no 12-month rate for October; on our interpolated October 2025 base, headline inflation is 4.0% against 3.7% in September.
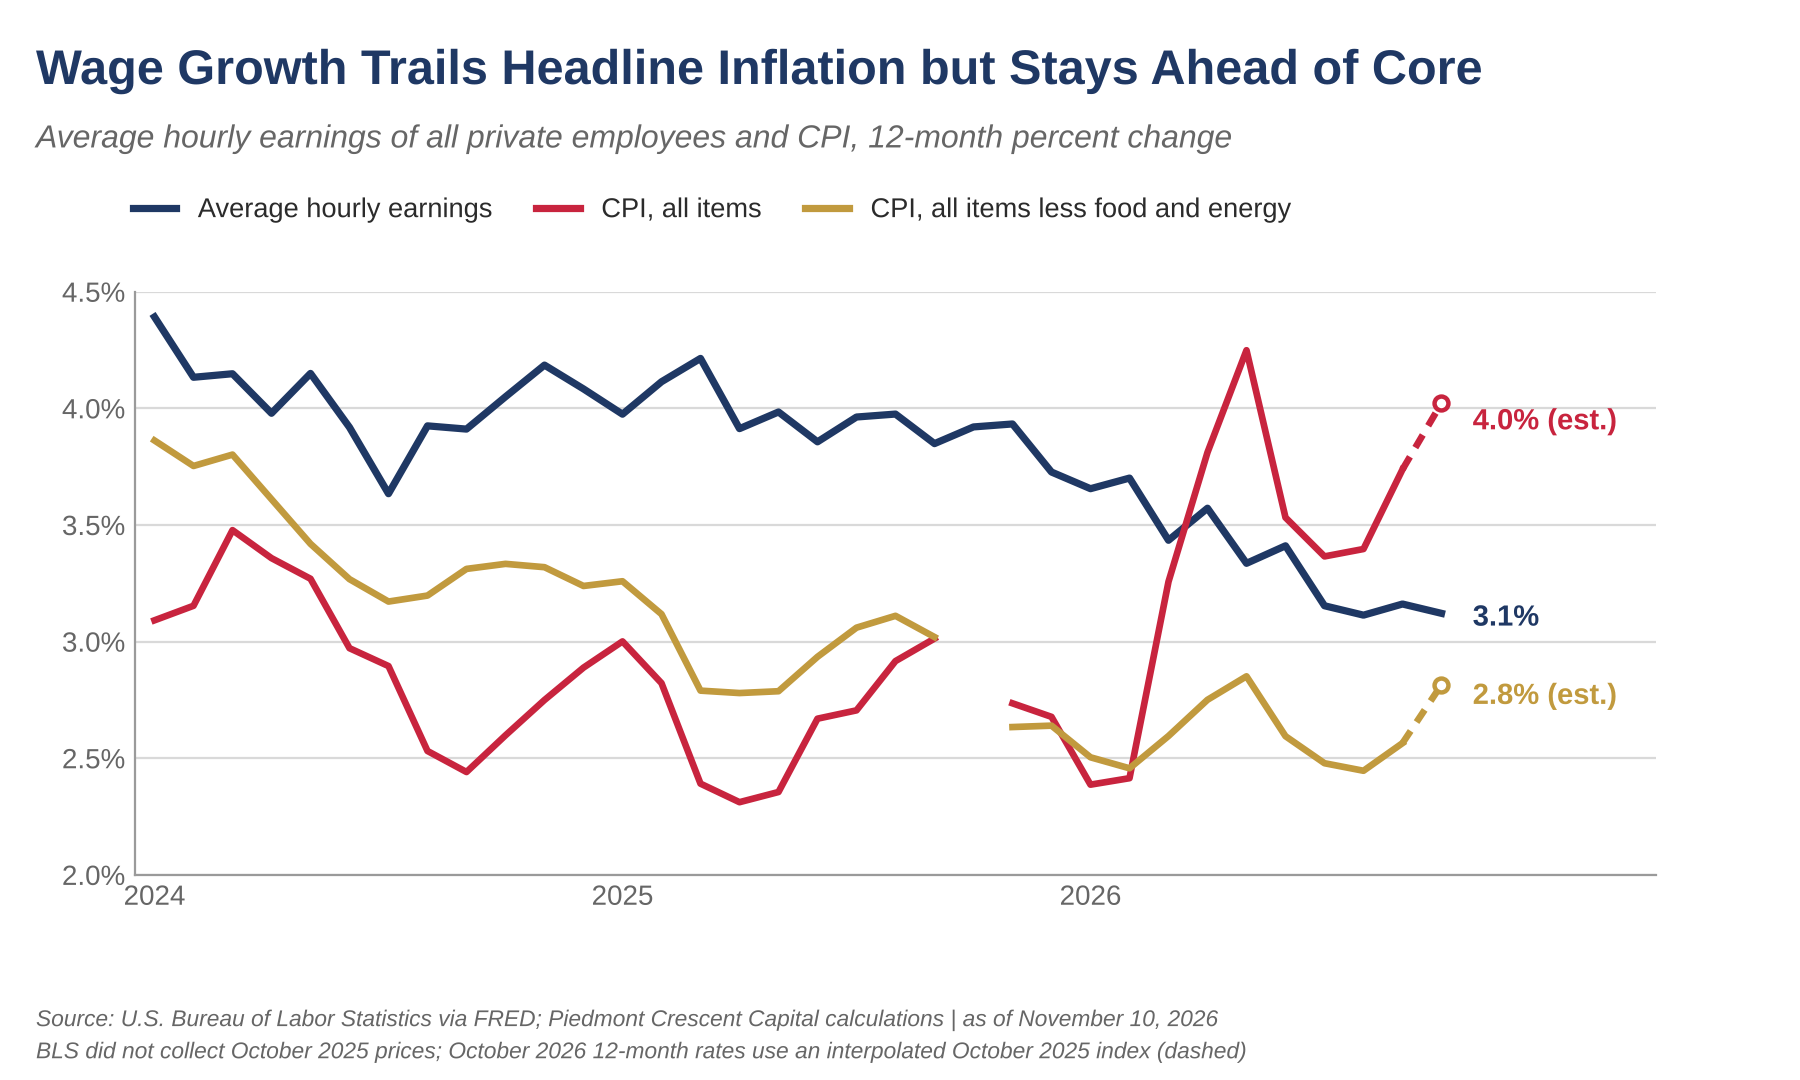
- Real wages stopped falling. Average hourly earnings rose 0.4% in October to $38.00, matching the 0.4% rise in the CPI-U, so real hourly earnings were unchanged on the month after a 0.4% decline in September. Nominal wage growth of 3.1% over the past year compares with estimated core inflation of 2.8% and headline inflation of 4.0%.
Key Takeaways
| Key Concept | Findings |
|---|---|
| Headline CPI | Rose 0.4% in October after rising 0.6% in September, a tenth above the 0.3% consensus. BLS publishes no 12-month rate for October; on our interpolated base the rate is 4.0%, against 3.7% in September. |
| Energy | Up 0.7% on the month after 5.2% in September. Gasoline rose 1.0% seasonally adjusted (down 0.7% before adjustment) and fuel oil rose 2.0%. |
| Core CPI | Rose 0.3% for a third straight month against a consensus of 0.2%. On our interpolated base the 12-month rate is 2.8%, against 2.6% in September. |
| Core services outside housing | Rose about 0.39% in October after 0.34% in September and 0.41% in August, a three-month average of 0.38% (4.6% annualized). |
| Shelter | Rose 0.3% after 0.4% in September. Owners’ equivalent rent rose 0.3% and rent 0.2%; lodging away from home rose 0.6%. |
| Underlying trend | Our HP-filter trend for core CPI rose to 2.65% from 2.61%, a third straight increase. The headline trend rose to 3.29% from 3.23%. |
| Real earnings | Real average hourly earnings were unchanged in October after falling 0.4% in September, as a 0.4% rise in earnings matched a 0.4% rise in the CPI. |
| Our call | The Committee held at 3.75% to 4.00% on October 28 on a 10-2 vote, with Cook and Hammack dissenting for a hike. We expect a hike on December 9 and at least one more in 2027. |
The Overview
October’s CPI delivered a headline a tenth above consensus and a core reading a tenth above it as well. The all items index rose 0.4% after rising 0.6% in September, against a consensus of 0.3%. The increase was broad. BLS says shelter accounted for more than 30% of it, food rose 0.5% and energy rose 0.7%. Core prices rose 0.3% against a consensus of 0.2%, matching September and August. BLS did not collect October 2025 prices during the federal government shutdown and does not publish a 12-month change for October. On the interpolated base described in our methodology note, the 12-month rate is 4.0% for headline and 2.8% for core, against 3.7% and 2.6% in September.
The core surprise is small on its face, but it is the second in a row and it came from the same places. Services outside housing ran hot again, and shelter, though it eased to 0.3%, is still running above its summer pace. The report arrives less than two weeks after the Committee held the funds rate at 3.75% to 4.00% on October 28 on a 10-2 vote, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of a quarter-point increase, and four weeks before the December 8-9 meeting. It adds to the evidence that the Committee has more work to do.
Energy and Food: Gasoline Cools, Groceries Heat Up
The energy index rose 0.7% in October after rising 5.2% in September. Gasoline rose 1.0% on a seasonally adjusted basis after advancing 9.1% in September; before seasonal adjustment, pump prices fell 0.7%. Fuel oil, a thin and volatile series that gives the earliest read on winter heating costs, rose 2.0% after rising 15.3% in September. Electricity rose 0.9% and natural gas fell 0.8%. Food rose 0.5% after being flat in September. Food at home rose 0.4% and food away from home rose 0.5%, with full service meals up 0.7%. Grocery prices are the line we would watch most closely. Diesel, which moves the trucks that stock grocery shelves, averaged $6.29 a gallon in September, up from $4.96 in July, and was running near $6.25 in October, according to Energy Information Administration data. Freight costs reach shelf prices with a lag, so we think the rise in diesel is a likely driver of the 0.4% gain in food at home and a reason to expect further firmness in grocery prices in the months ahead.
Core Inflation: A Third Straight 0.3%, With Services in the Lead
The core index rose 0.3% in October, as it did in September and August, against a consensus of 0.2%. Core goods cooled, with commodities less food and energy up 0.2% after 0.3% in September. Used vehicles fell 1.2% after rising 0.7%, new vehicles rose 0.2% and apparel rose 0.1%. Services did the rest. Recreation rose 0.8%, hospital services 0.8%, motor vehicle insurance 0.7% and education 0.3%, while medical care overall rose 0.3% after 0.1% in September. Communication fell 0.1%.
Services less energy services and shelter, our measure of core services outside housing and the one we said in July we would be watching, rose about 0.39% in October after 0.34% in September and 0.41% in August. That is a three-month average of 0.38%, or 4.6% annualized, against 3.1% over the twelve months through September. (This is our calculation from the BLS seasonally adjusted indexes.) Transportation services rose 0.8% after 0.6% in September and 0.5% in August, and airline fares rose 0.4% after 1.2% in September. This is the pace we flagged in July, and it has now held for four months.
The Underlying Trend: Our HP-Filter Read
Our HP-filtered estimate of trend core inflation rose to 2.65% in October from 2.61% in September, a third straight increase after declines in May, June and July. The trend is still well below the 3.12% reading from a year ago, but the direction has now changed three times running. Core CPI has compounded at a 3.75% annual rate over the past three months, up from 3.41% in September and above both its six-month pace of 2.69% and its 12-month pace of 2.77%. The six-month pace fell from 2.85% as April’s 4.6% annualized gain dropped out of the window. The three-month rate has now sat above the 12-month rate for two months running.
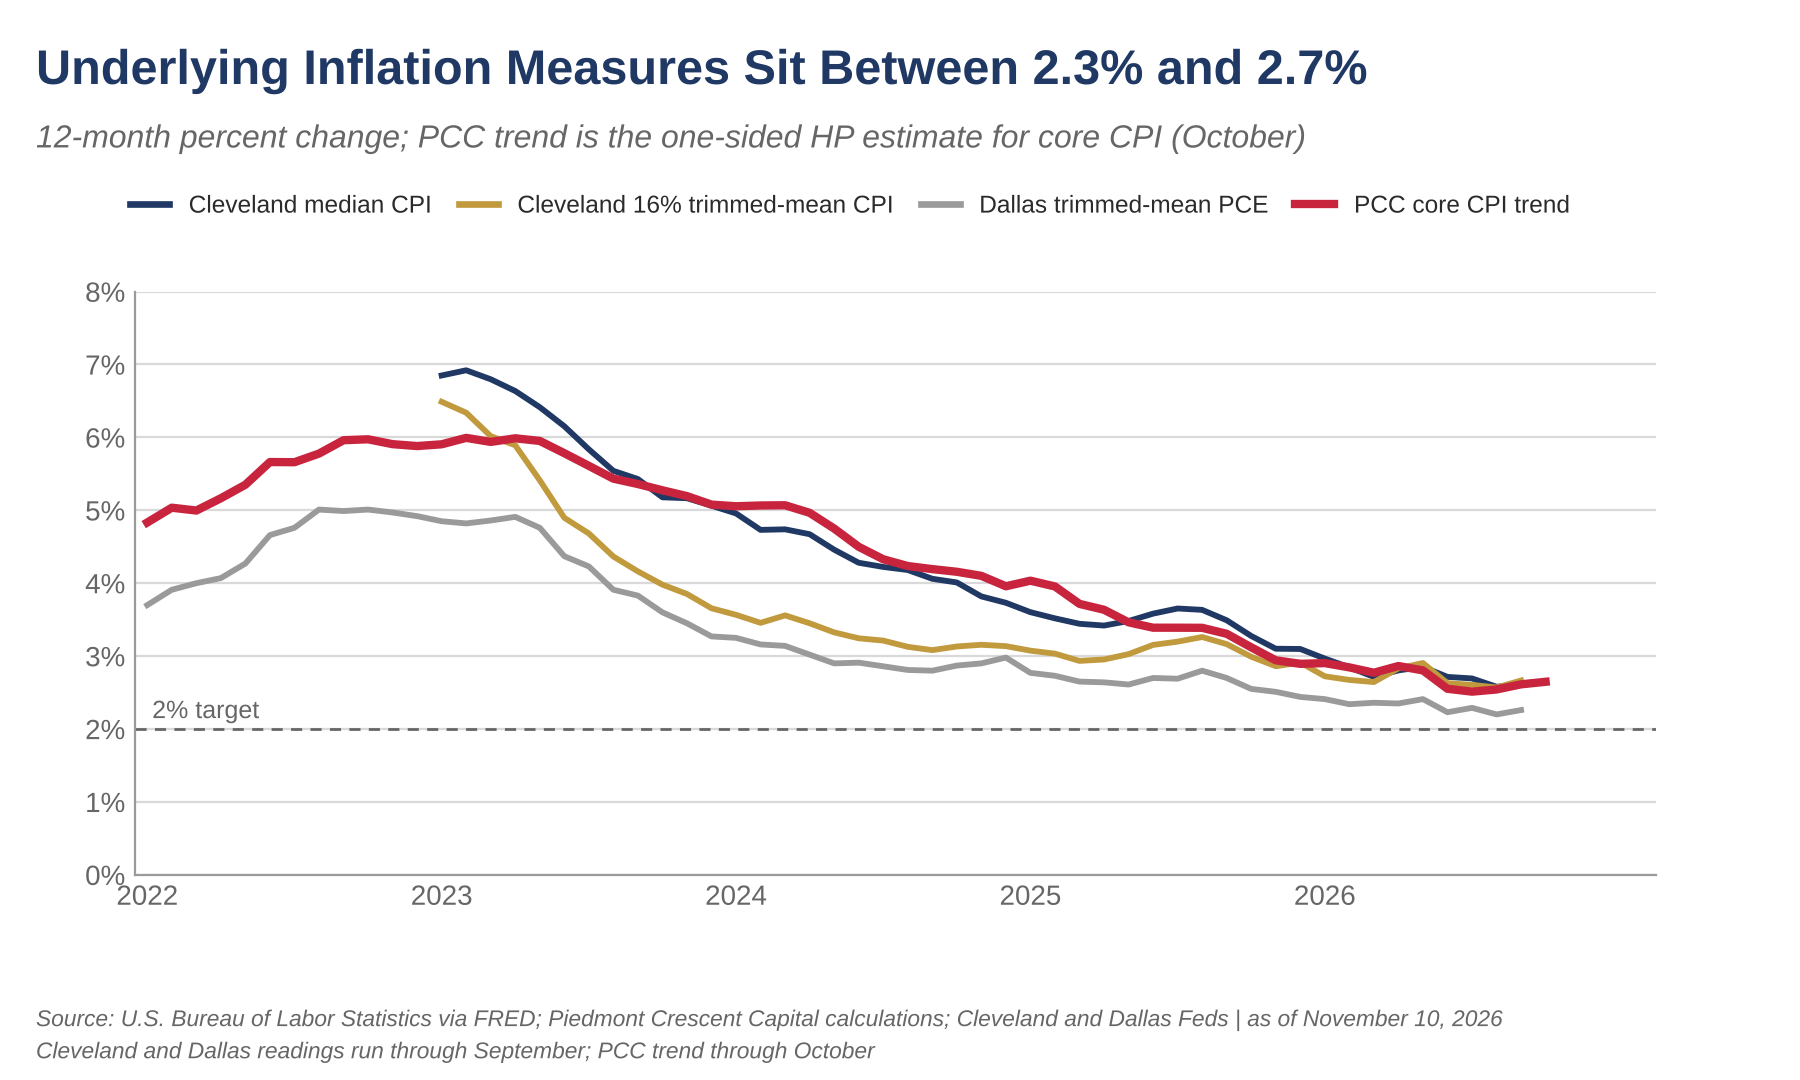
The alternative measures we track put the level in a band between 2.3% and 2.7%. The Cleveland Fed’s October median and trimmed-mean readings were not yet available, but the September readings of 2.61% and 2.67% were both higher than August’s. The Dallas Fed’s trimmed mean PCE, which lags by a month, was 2.26% in September, up from 2.20% in August. Every measure that strips out the largest one-month moves is leaning the same way as ours.
Methodology note. We apply a one-sided Hodrick-Prescott filter to monthly annualized inflation with the standard monthly smoothing parameter (λ = 129,600), computed on seasonally adjusted headline and core CPI index levels from a 2000 sample start. The one-sided implementation uses only data available through the current month, so the estimate is real-time and does not revise as future data arrive. October 2025 has no CPI observation because of the 2025 lapse in appropriations; we interpolate the index level geometrically between September and November, which moves the trend estimate by less than a basis point. Because BLS does not publish a 12-month change for October 2026, the 12-month rates we cite for October use the same interpolated October 2025 index level.
Shelter and Light Vehicles: Housing Eases a Notch While Vehicles Cool
Monetary policy reaches consumer prices mainly through two interest-sensitive channels, and this month housing eased a notch. Shelter rose 0.3% in October after 0.4% in September, 0.3% in August and 0.2% in July. Owners’ equivalent rent rose 0.3% and rent of primary residence rose 0.2%. Lodging away from home rose 0.6% after a 2.0% gain in September, a volatile line item that accounted for part of September’s acceleration. Shelter has now risen 0.26%, 0.39% and 0.30% in the past three months, so it has not resumed the slowing that marked the early summer, even though October was a step back from September. Shelter is not likely to be the moderating influence over the next year that it was over the last. Apartment rents are rising in more markets today than they were a year ago, and in the markets where rents are still falling the declines are smaller, because demand is holding up well.
Used vehicle prices fell 1.2% after rising 0.7% in September and were down 3.3% over the twelve months through September, while new vehicles rose 0.2% and were up 0.7% over the same span. Core goods as a group cooled to 0.2% from 0.3%. In July we described housing and vehicles as the evidence that policy was biting. October gave that evidence some support from vehicles, but one soft month in used cars, a volatile line, does not offset firm services.
Travel and Transportation: The Forward-Looking Signal
Two categories in this release say more about the months ahead than about October. Airline fares rose 0.4% after rising 1.2% in September, 2.7% in August and 3.8% in July, a slower pace. Transportation services broadly rose 0.8% after rising 0.6% in September. Fares and transportation services tend to move with fuel-cost pass-through and discretionary travel demand before the effect shows up elsewhere, which makes gasoline’s 37.4% gain over the twelve months through September a risk for core services in the coming months.
Fuel oil rose 2.0% in October after 15.3% in September and 10.1% in August. It is a thinly weighted line and it has reversed sharply before, so a few months of data should not be treated as destiny. It remains the earliest data point on heating costs heading into winter, though, and we will be watching the November print closely.
Real Earnings: The Squeeze Pauses
The companion release showed real wage erosion pause. Average hourly earnings for all private employees rose 0.4% in October to $38.00, while the CPI-U also rose 0.4%, so real hourly earnings were unchanged on the month after falling 0.4% in September and 0.1% in August. Real average weekly earnings were unchanged as well. The CPI-W for production and nonsupervisory workers, which carries more weight on gasoline, rose 0.3%, so real hourly earnings for those workers rose 0.1%, although a 0.3% drop in their workweek cut real weekly earnings by 0.3%. BLS does not publish an over-the-year comparison for real earnings this month because October 2025 prices were not collected.
Nominal average hourly earnings are up 3.1% over the past year, down from 3.2% in September, against an estimated 4.0% rise in headline consumer prices and 2.8% in core prices on our interpolated base. Wage growth now trails the headline by 0.9 percentage point and leads core by 0.3 point, a narrower cushion over core than the 0.6 point it held in September. October’s employment report, with payroll growth of 165,000, upward revisions of 84,000 to August and September, and an unemployment rate of 4.1%, showed a firmer labor market than the September report suggested, yet it gave households little evidence of faster wage gains as hourly earnings growth edged down. The lack of real income growth was the driving force behind the midterm elections, and groceries and fuel are the prices households notice first.
What Households and Markets Expect
The New York Fed’s Survey of Consumer Expectations for October, released on November 9, showed no change in inflation expectations. Median one-year expectations held at 3.9%, three-year expectations at 3.3% and five-year expectations at 3.0%. Labor market expectations were mixed. The mean probability that unemployment will be higher in a year rose 1.4 percentage points to 45.3%, the highest reading since April 2020, driven by respondents without a college degree. The perceived probability of losing one’s job rose 0.4 point to 13.9%, still below its 12-month average of 14.3%, and the perceived probability of finding a job after a loss rose 0.4 point to 46.5%, the highest since November 2025.
The University of Michigan’s preliminary November survey, released on November 6, was more encouraging. Its sentiment index rose to 51.0 from 48.0, and both inflation-expectations gauges eased: year-ahead expectations to 4.3% from 4.7%, and long-run expectations to 3.4% from 3.5%. Both gauges remain elevated, so the improvement gives the Committee some relief and no more than that.
Markets are calmer than households. The five-year, five-year forward inflation compensation rate stood at 2.19% on November 9, the latest reading available to us and one that predates this release, down from near 2.3% a month earlier. Investors do not appear to read three straight 0.3% core prints as the start of a new trend, which is where a fourth could change the conversation.
Our Call · A December Hike and At Least One More in 2027
We expect the Committee to hike on December 9. The Committee held the funds rate at 3.75% to 4.00% on October 28 on a 10-2 vote, with Governor Cook and Cleveland Fed President Hammack dissenting in favor of a quarter-point increase. October’s report, with the headline a tenth above consensus and core a tenth above for the second month in a row, adds to the case they made. The Committee will also have the November employment report in hand before it meets on December 8-9. Governor Waller, speaking in London on November 10, said he is leaning toward supporting a quarter-point increase in December and that a 50 basis point hike should be considered if October inflation looked like the prior two months, arguing that a 25 basis point move alone would put the Fed’s credibility at risk. We doubt the Committee will go that far unless we see significantly more signs of accelerating inflation. October matched the recent pattern, with core up 0.3% for a third straight month and core services outside housing near 0.4%, which is firm but not accelerating. A half-point increase would need a clear step up in those readings, in the three-month core rate and in inflation expectations. A 50 basis point hike nonetheless remains a risk, and one that would grow if the November data show a further acceleration. Politics adds to the pressure. With real incomes at the center of the midterms, we expect Congress to look to the Fed for more tangible results in curbing inflation by the 2028 election.
The threshold we laid out in July still holds, and it supports the December hike. In July we said two or three more months of core services less shelter near 0.4%, with shelter no longer decelerating, would tell us policy was less restrictive than we thought. Services outside housing ran 0.35%, 0.41%, 0.34% and about 0.39% in July through October, and shelter has run 0.14%, 0.26%, 0.39% and 0.30% over the same months. We still see the broader trend as well below where it stood a year ago, and a funds rate of 3.75% to 4.00% against core inflation of about 2.8% is a positive real rate. But a trend that has risen three months running, in the part of the index that policy reaches last, is the acceleration in the core numbers we follow most closely, and it tells us the Fed has more work to do, which is what we expected.
Our call is the December 9 increase and at least one more in 2027, which would take the funds rate to 4.25% to 4.50%. The pace beyond that depends on how resilient the economy and financial markets prove to be. Every reaction function says what the Committee would do if nothing else changed, and something else always changes. Our own signal for the other direction is core services outside housing falling back to 0.2% or less for two months with shelter returning to its summer pace, which is a harder bar to clear now that rents are firming in more markets. Employment is the other piece. Payroll growth of 165,000 in October, upward revisions of 84,000 to August and September and an unemployment rate of 4.1% describe a labor market that is firmer than the September report suggested. A resilient economy and calm markets would support more than one further increase, while a break in either would take the 2027 hike off the table.
Mark P. Vitner – Chief Economist, Piedmont Crescent Capital
mark.vitner@piedmontcrescentcapital.com · (704) 458-4000
Appendix: Trend Inflation Estimates
| Measure | Latest | Prior month |
|---|---|---|
| PCC HP-filter trend, core CPI (one-sided, λ=129,600) | 2.65% (Oct) | 2.61% (Sep) |
| PCC HP-filter trend, headline CPI | 3.29% (Oct) | 3.23% (Sep) |
| Core CPI, compound annual rate over three months | 3.75% (Oct) | 3.41% (Sep) |
| Core CPI, compound annual rate over six months | 2.69% (Oct) | 2.85% (Sep) |
| Cleveland Fed median CPI (12-month percent change) | 2.61% (Sep) | 2.58% (Aug) |
| Cleveland Fed 16% trimmed-mean CPI (12-month percent change) | 2.67% (Sep) | 2.57% (Aug) |
| Dallas Fed trimmed mean PCE (12-month rate) | 2.26% (Sep) | 2.20% (Aug) |
| Core CPI, 12-month (October on the interpolated base) | 2.8% (Oct) | 2.6% (Sep) |
Computation notes. HP-filter estimates were computed on seasonally adjusted headline and core CPI index levels (BLS, through FRED series CPIAUCSL and CPILFESL for July through October; earlier months as in prior reports) through October 2026, sample from 2000, one-sided recursive expanding-window implementation, λ = 129,600, applied to monthly annualized inflation. The September core and headline trends of 2.61% and 3.23% are unchanged from last month’s report. Core services outside housing for October is our calculation from the BLS seasonally adjusted indexes for services less energy services (CUSR0000SASLE) and shelter (CUSR0000SAH1), using September relative-importance weights; earlier months are the Macrobond series uspric6189 as published. Shelter is uspric2170. Cleveland Fed median and trimmed-mean CPI are Macrobond series uspric0015 and uspric0013, and the Dallas Fed trimmed mean PCE is uspric0050, with the September Dallas value from FRED series PCETRIM12M159SFRBDAL. Average hourly earnings are uslama0001 and uslama0218. Real earnings are as published by BLS. The five-year, five-year forward breakeven is FRED series T5YIFR.
Sources: U.S. Bureau of Labor Statistics, Consumer Price Index and Real Earnings, October 2026, and Employment Situation, October 2026; Board of Governors of the Federal Reserve System, FOMC statement of October 28, 2026; remarks of Governor Waller, London, November 10, 2026, as reported by American Banker; Federal Reserve Bank of Cleveland, median and 16% trimmed-mean CPI; Federal Reserve Bank of Dallas, trimmed mean PCE; Federal Reserve Bank of New York, Survey of Consumer Expectations, October 2026; University of Michigan, Surveys of Consumers, preliminary November 2026; U.S. Energy Information Administration, retail diesel prices, via FRED series GASDESM; Federal Reserve Bank of St. Louis, FRED; Macrobond; Piedmont Crescent Capital calculations.
Disclaimer: This report is provided for informational purposes only and does not constitute investment, legal, tax, or accounting advice, nor an offer or solicitation to buy or sell any security. Information is drawn from sources believed to be reliable, including the U.S. Bureau of Labor Statistics and the Federal Reserve Banks of Cleveland, Dallas, New York and St. Louis, but its accuracy and completeness are not guaranteed. Views expressed are those of the author as of the date of publication and are subject to change without notice. Past performance is not indicative of future results.