Production Jumped as Factory Strength Broadened
The Manufacturing PMI rose 1.0 point to 55.5 in October, a larger increase than expected, with all five components in expansion. Production was at its highest since November 2021 and 11 industries reported higher orders, output and backlogs, while the Prices Index eased 2.7 points to 75.2, which is still too high. The regional surveys were mixed this past month.
Early Signals
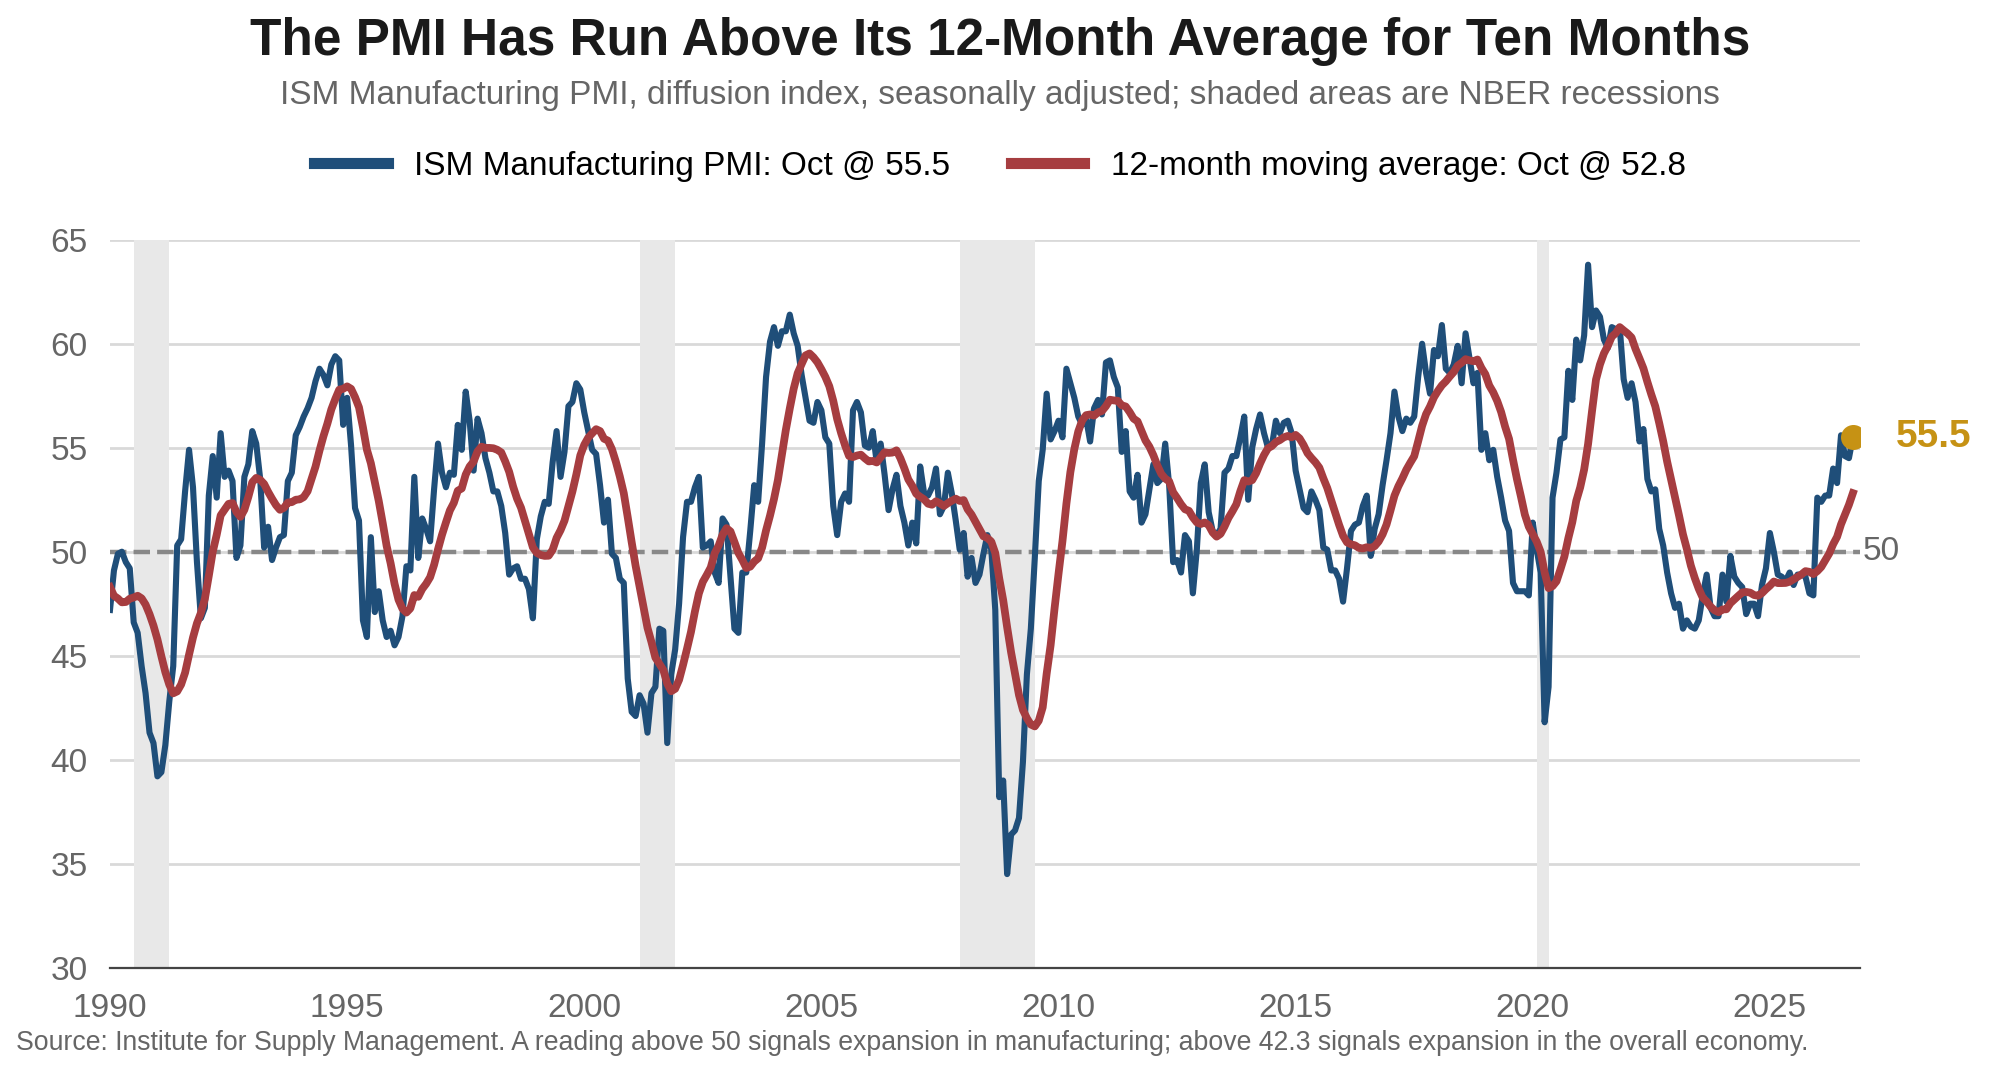
- The expansion strengthened. The Manufacturing PMI rose 1.0 point to 55.5 in October from 54.5 in September, above the consensus forecast of 54.6 and the tenth consecutive month above 50. ISM says that reading corresponds to real GDP growth of 2.7 percent at an annual rate, up from 2.4 percent in September.
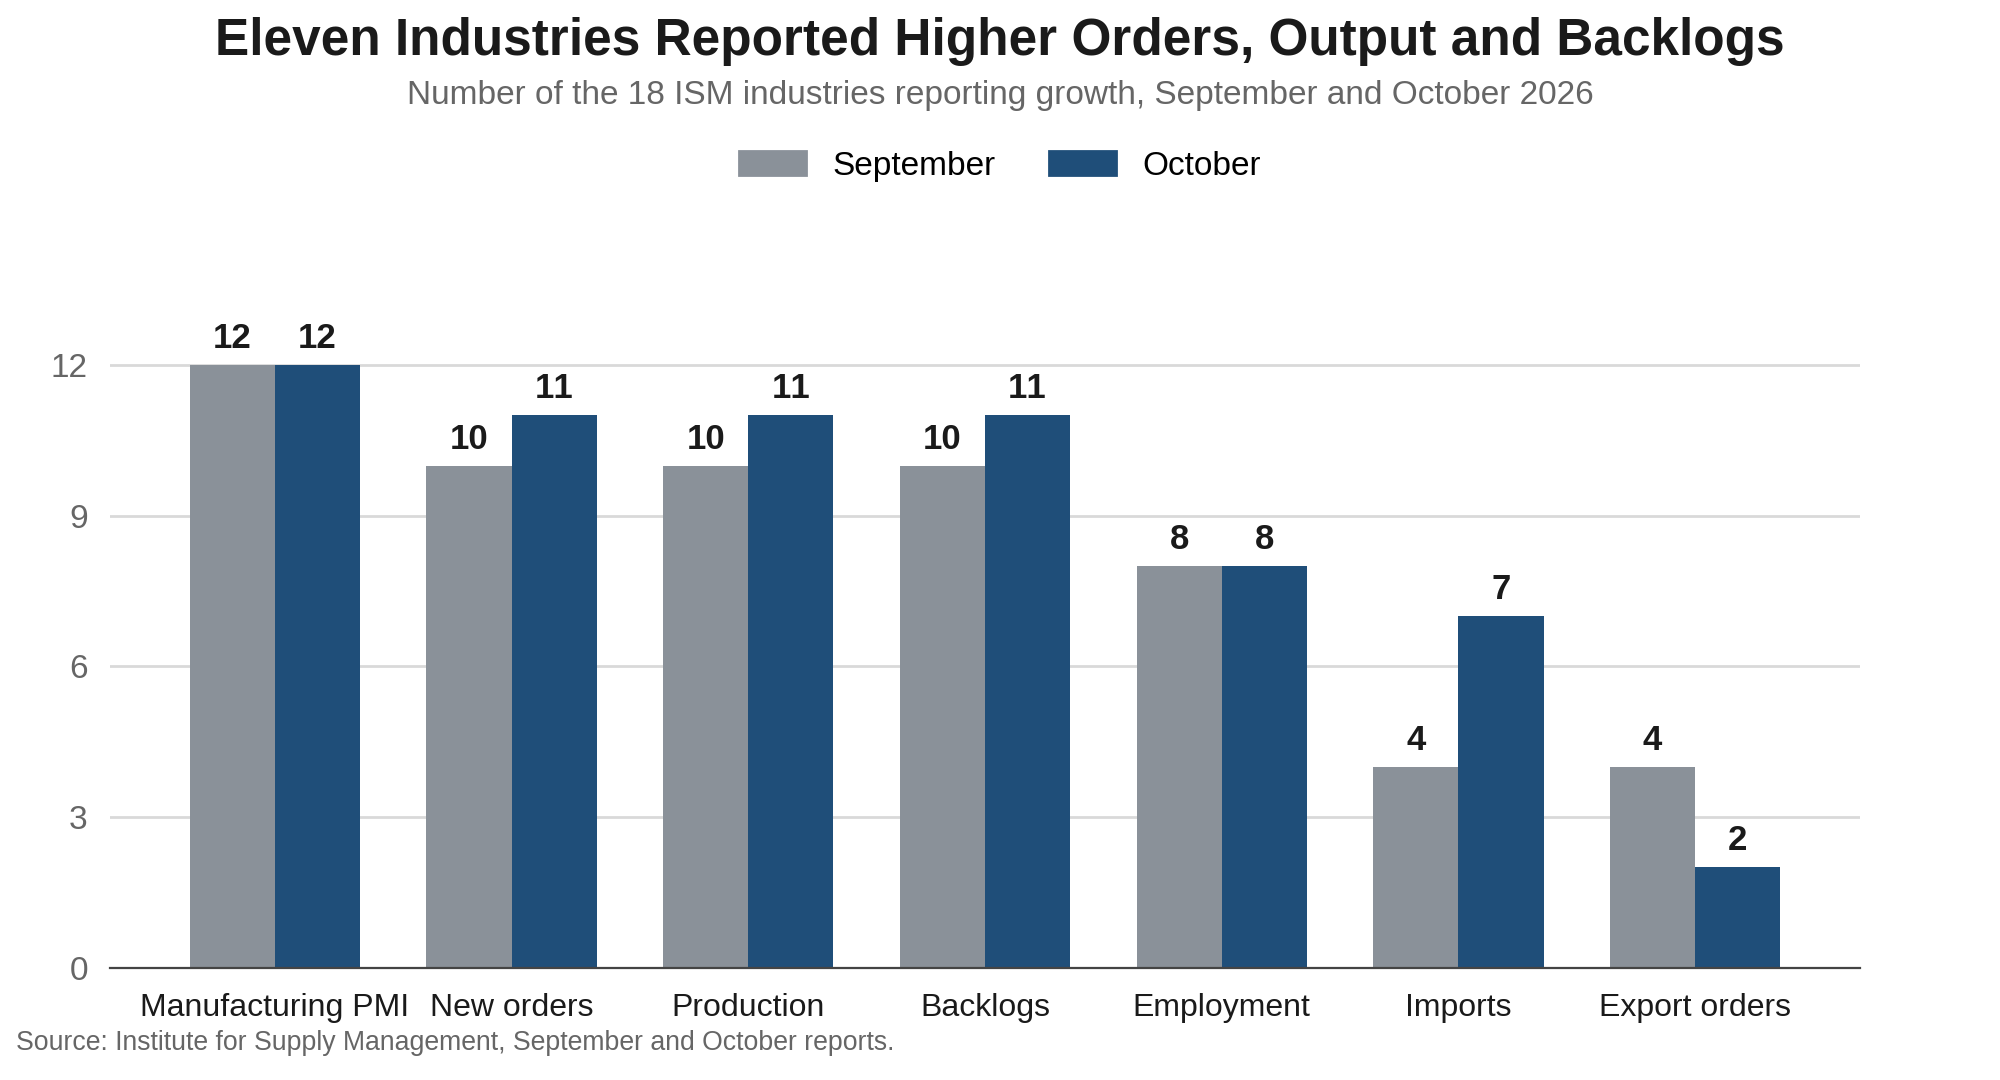
- Strength broadened. Eleven industries reported growth in each of new orders, production and backlogs, up from 10 in September, and all five PMI components were in expansion, with production at 59.0, its highest reading since November 2021, and inventories back above 50 at 51.4. That breadth is one of the key reasons our forecast for 2027 is above consensus.
- Orders held and hiring cooled slightly. The New Orders Index rose 0.2 point to 55.5 and the Backlog of Orders Index fell 1.8 points to 54.6. Both series, however, have now been in expansion for ten months. The Employment Index slipped 0.3 point to 52.4, a fourth month above 50, while the ratio of positive to negative comments on hiring widened to 1.8 to 1 from 1.5 to 1.
- Prices eased from a very high level. The Prices Index fell 2.7 points to 75.2, a 25th month of rising input costs, but the producer price index for intermediate goods accelerated to 14.1 percent year over year in September, its highest since August 2022. The share of respondents paying more fell to 53.1 percent from 58.6 percent.
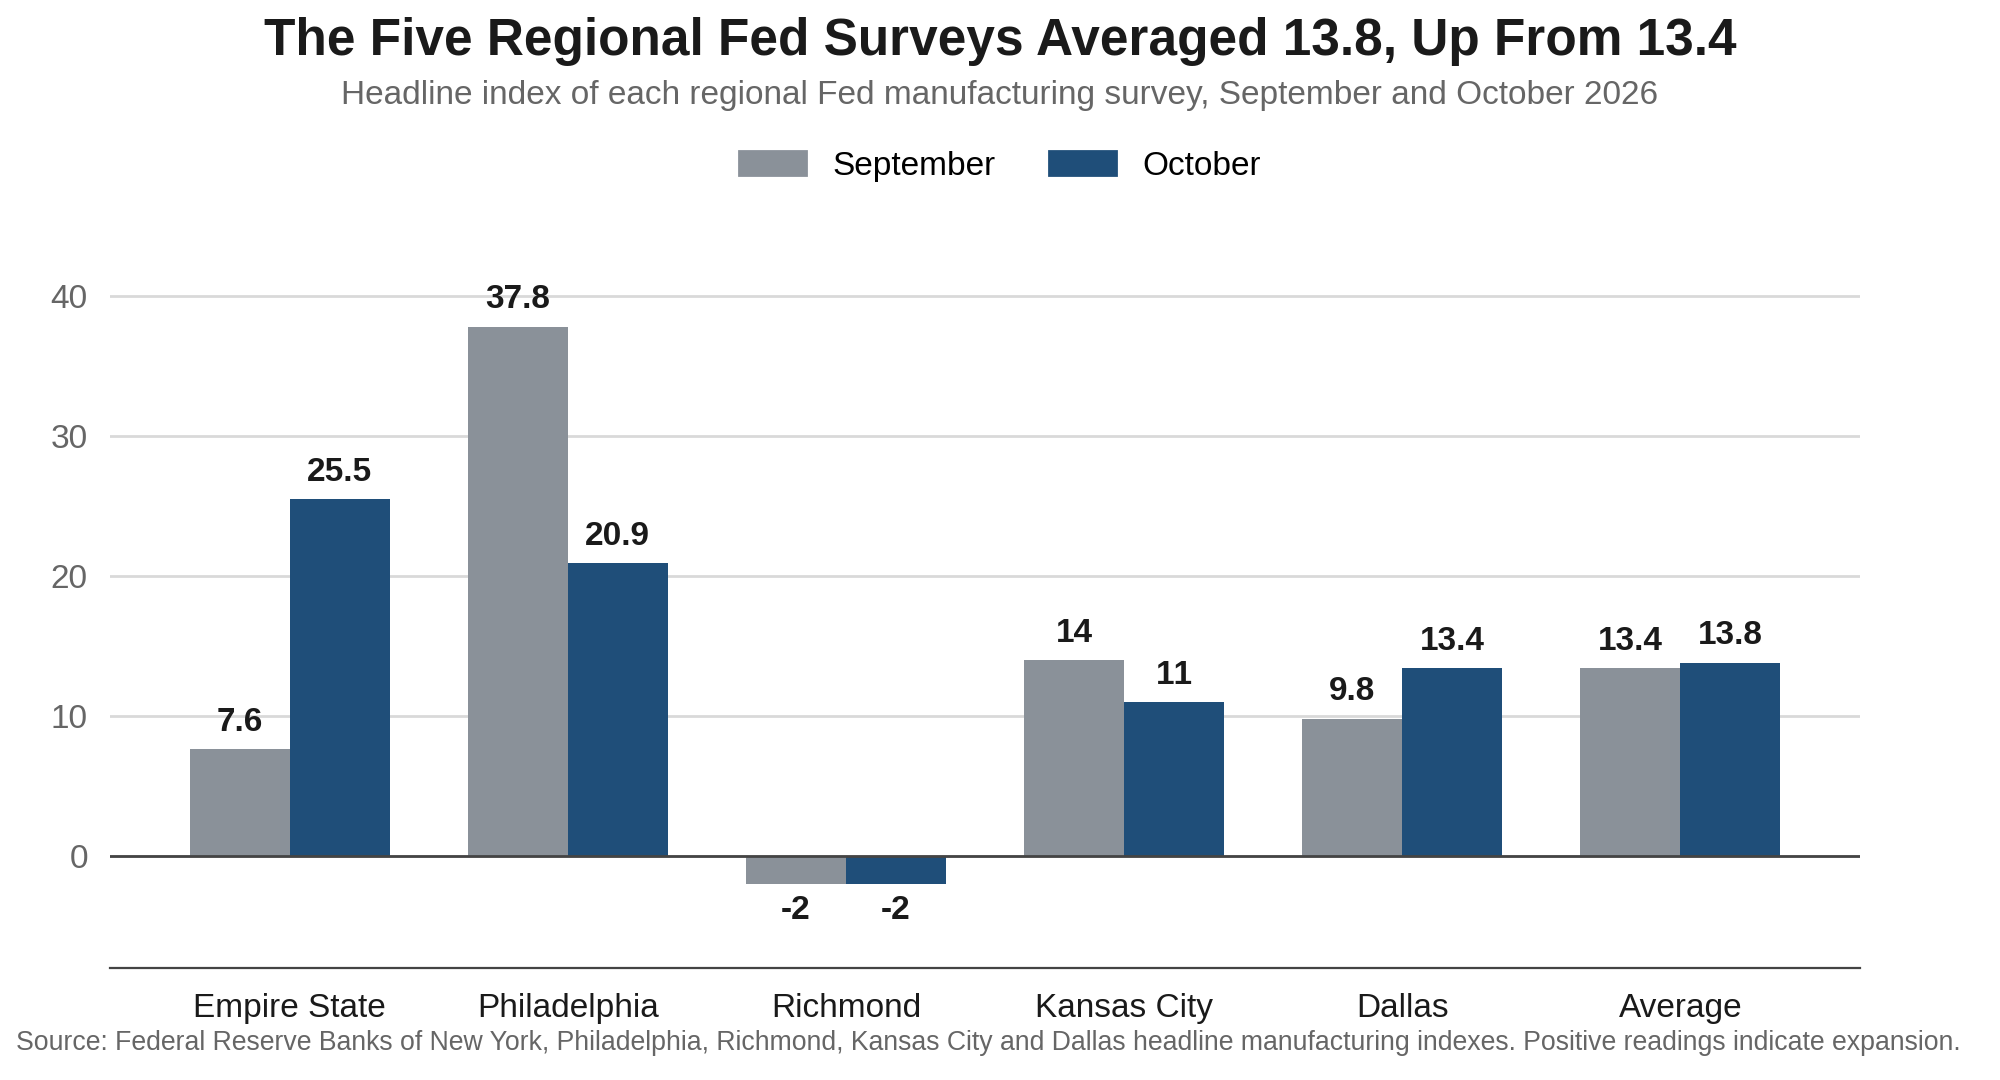
- This past month’s regional surveys were mixed. The Chicago Business Barometer fell 3.5 points to 55.3 while its employment index jumped 10.3 points, and the average of five regional Fed surveys edged up to 13.8 from 13.4, with Empire State (25.5) and Dallas (13.4) stronger, Philadelphia (20.9) and Kansas City (11) weaker, and Richmond unchanged at a negative 2 and the lone outlier. The Richmond district includes Virginia, Washington D.C., Maryland, the Carolinas and most of West Virginia, and conditions within it vary. Payrolls over the past year are down in Washington D.C. (-3.5 percent) and Virginia (-0.6 percent), while the Carolinas are growing faster than the nation in both employment (North Carolina +1.3 percent, South Carolina +2.3 percent, against +0.3 percent for the U.S.) and population (+1.3 percent and +1.5 percent in 2025).
Key Takeaways
| Key Concept | Findings |
|---|---|
| Manufacturing PMI | Rose to 55.5 from 54.5, a tenth consecutive month above 50 after a ten-month contraction. The 12-month average is 52.8, with a high of 55.6 in July and a low of 47.9 in December. ISM relates that reading to real GDP growth of 2.7 percent at an annual rate. |
| New Orders and Backlogs | New orders rose 0.2 point to 55.5 and backlogs fell 1.8 points to 54.6, both a tenth month of growth. Customers’ inventories were unchanged at 41.6 and have been judged too low for 25 consecutive months, a condition that has tended to come before a rise in production. The unadjusted new orders index slipped to about 53.7 from 54.0. |
| Production | Up 2.3 points to 59.0, a 12th consecutive month of growth and the highest reading since November 2021. The unadjusted index rose about 1.3 points to 58.1, so more than half of the gain shows up before seasonal adjustment. |
| Employment | Down 0.3 point to 52.4, a fourth month in expansion after 17 straight months below 50. Positive comments on hiring outnumbered negative ones 1.8 to 1, up from 1.5 to 1, and the unadjusted index rose to about 51.8 from 50.4. |
| Prices | Down 2.7 points to 75.2, a 25th month of increases. The share paying more fell to 53.1 percent from 58.6 percent, while the share paying less was unchanged at 2.8 percent. The producer price index for intermediate goods was up 14.1 percent from a year earlier in September. |
| Supplier Deliveries | Slower for an 11th month, at 59.1, up 0.1 point from September. Electronic components have been in short supply for 20 consecutive months, electrical components for 16 and memory for 10. |
| Trade | New export orders rose 0.3 point to 51.2 and the Imports Index rose 1.9 points to 52.9, both in expansion. Seven industries reported higher imports, up from four, while only two reported higher export orders, down from four. |
| Breadth | Twelve of 18 industries grew and three contracted, Printing & Related Support Activities, Paper Products and Nonmetallic Mineral Products. Eleven industries reported growth in each of new orders, production and backlogs, up from 10. By GDP weight, the contracting share rose to 6 percent from 2 percent. Five of the six largest industries expanded. |
| 2027 Forecast | Broadening strength in manufacturing is one of the key reasons our forecast for 2027 real GDP growth of 2.6 percent is above the 2.2 percent consensus. We look for manufacturing output to rise 2.9 percent in 2027 after 1.7 percent in 2026, with business inventories adding to growth after subtracting from it this year. |
| Regional Surveys | Chicago fell 3.5 points to 55.3, but its employment index jumped 10.3 points to its highest since April 2021. The average of five regional Fed surveys edged up to 13.8 from 13.4, while the average of their new orders indexes fell to about 6.4 from 16.0. |
| Policy Signal | The Committee held at 3.75 to 4.00 percent on October 28 with two dissents in favor of a quarter-point increase. Broadening orders and production alongside input costs near 75 support our call for an increase on December 9 to 4.00 to 4.25 percent and another in March to 4.25 to 4.50 percent, with June still an even call. |
The Overview
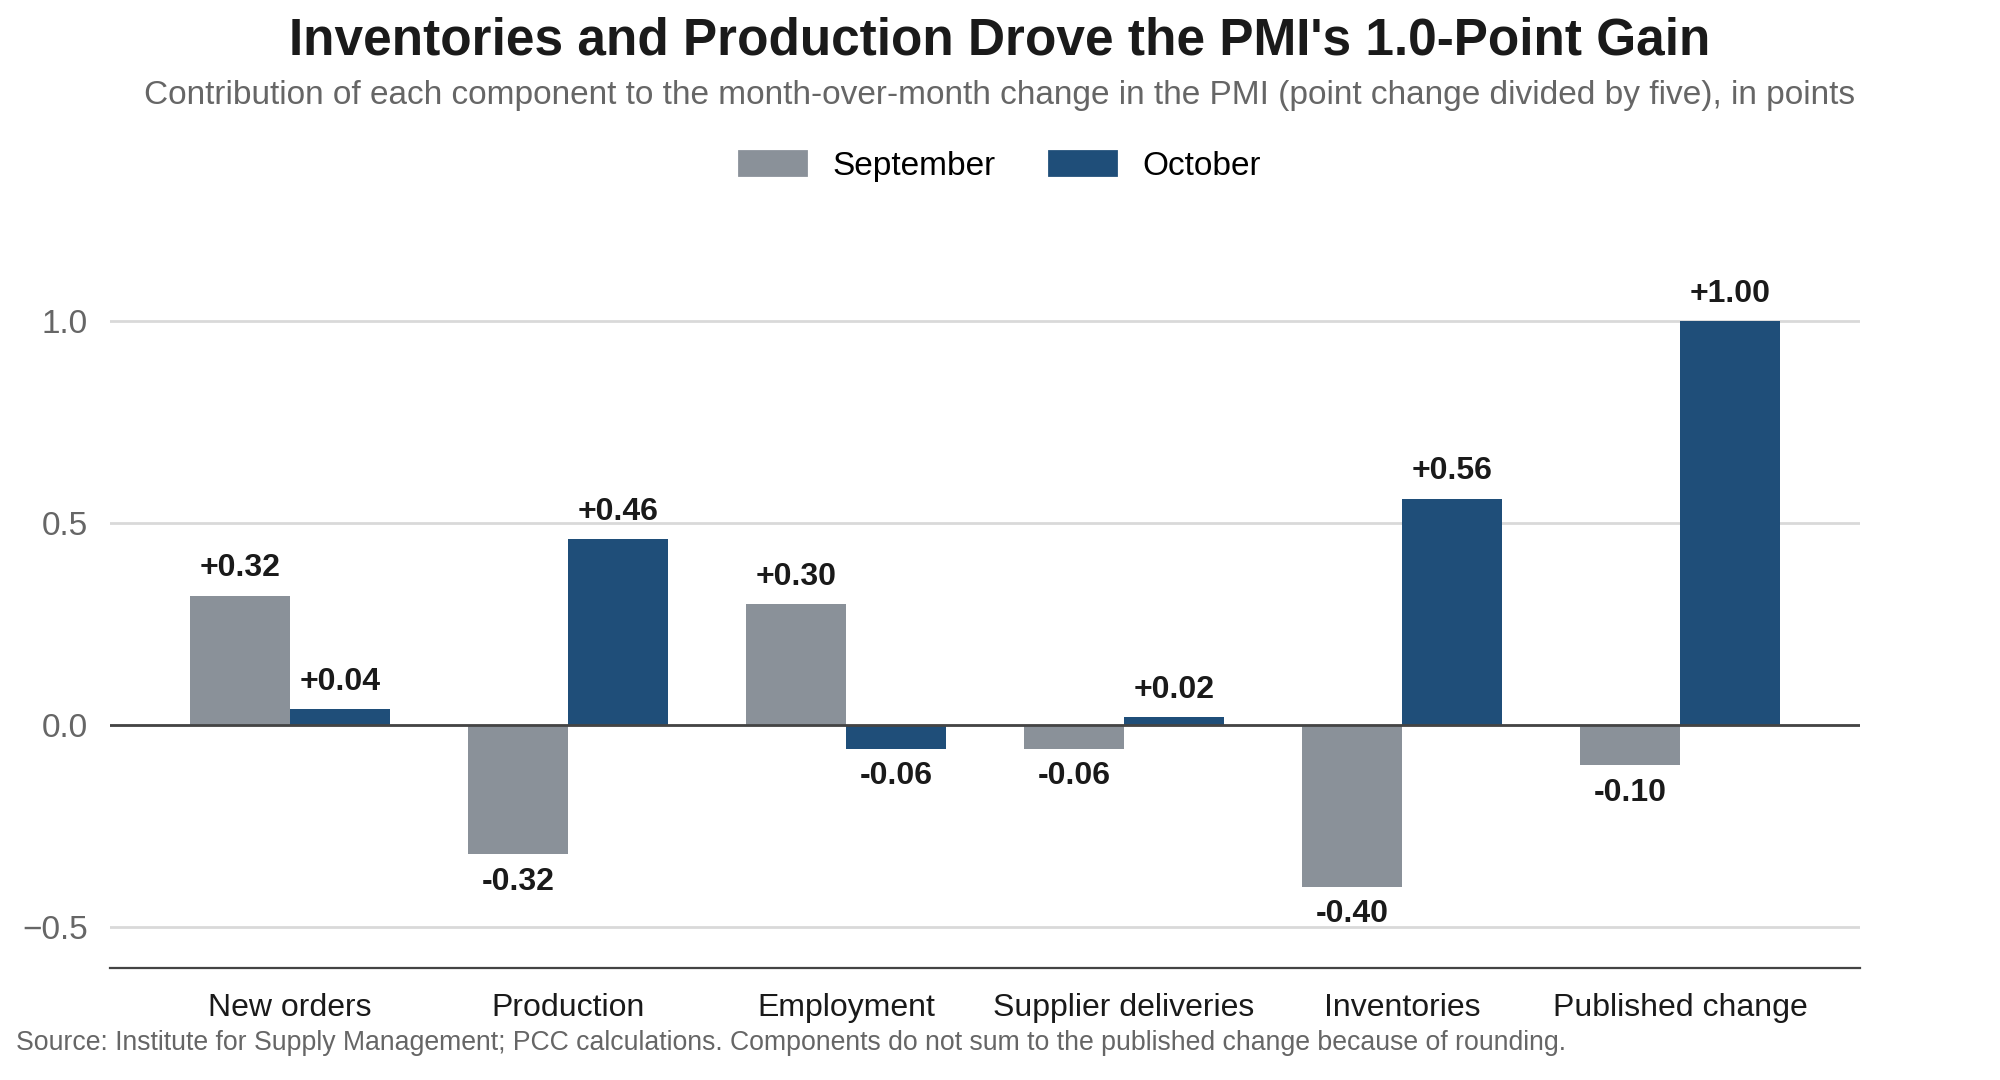
The Manufacturing PMI rose 1.0 point to 55.5 in October, its tenth consecutive month above 50 and 0.9 point above the 54.6 consensus. Inventories and production did most of the work, adding about 0.56 and 0.46 point to the index, while new orders (+0.04 point), supplier deliveries (+0.02 point) and employment (-0.06 point) together netted to zero. All five components were in expansion, with the Inventories Index back above 50 at 51.4 after slipping to 48.6 in September and the Production Index up 2.3 points to 59.0, the highest reading since November 2021. The gain in inventories appears to reflect firms beginning to rebuild stocks, since customers’ inventories, at an unchanged 41.6, have been judged too low for 25 consecutive months. Remember that the ISM index is a diffusion index and provides a reading on the breadth of the strength in the factory sector, not the magnitude of that strength. That said, the increasing breadth of those gains is a key reason for our above-consensus GDP forecast for 2027.
Twelve of 18 industries grew in October, the same number as in September, and the three that contracted are small. Printing & Related Support Activities, Paper Products and Nonmetallic Mineral Products contracted, and ISM reports that 6 percent of manufacturing GDP was contracting, up from 2 percent in September. On Bureau of Economic Analysis (BEA) figures those three industries, at $43 billion, $71 billion and $85 billion, come to about 7 percent of the sector’s $2.9 trillion in value added in 2025, close to the share ISM reports. Five of the six largest industries grew, and the number of industries reporting growth in each of new orders, production and backlogs rose to 11 from 10.
As we have said all year, factory payroll gains tend to follow a path in which orders improve, then backlogs build, then hours worked and production rise, and then hiring increases. The front of that chain held steady in October while the back of it kept improving. Last month we said October’s order readings would be the second of two that settle whether the recovery was building or fading. New orders edged up 0.2 point to 55.5 and backlogs gave back 1.8 points of September’s 4.6-point gain, to 54.6, which leaves both above 50 for a tenth month and above their August readings of 53.7 and 51.8. Average weekly hours in manufacturing rose to 42.0 in September, the highest since January 2019, and manufacturing payrolls added 9,000 jobs after 15,000 in August and 20,000 in July. Orders and backlogs are growing, hours are at their highest in more than seven years and hiring has risen for a fourth month, so the chain is intact and October’s readings are consistent with a recovery that is still building.
The Prices Index eased 2.7 points to 75.2, and the share of respondents paying more gave back 5.5 points of September’s 12.4-point jump. That left 53.1 percent paying more, with the share paying less unchanged at 2.8 percent and the share reporting no change up to 44.1 percent from 38.6 percent. A reading of 75.2 is still a 25th month of rising input costs, and the producer price data, discussed below, accelerated while the survey eased.
Orders Held and Backlogs Eased
New orders rose 0.2 point to 55.5 in October and the Backlog of Orders Index fell 1.8 points to 54.6, each a tenth consecutive month of expansion. Panel sentiment did not follow the indexes. Across all topics 66 percent of the comments were negative, up from 60 percent in September and the third consecutive month in which sentiment worsened, although the ratio of positive to negative comments on new orders improved to 1.8 to 1 from 1.7 to 1.
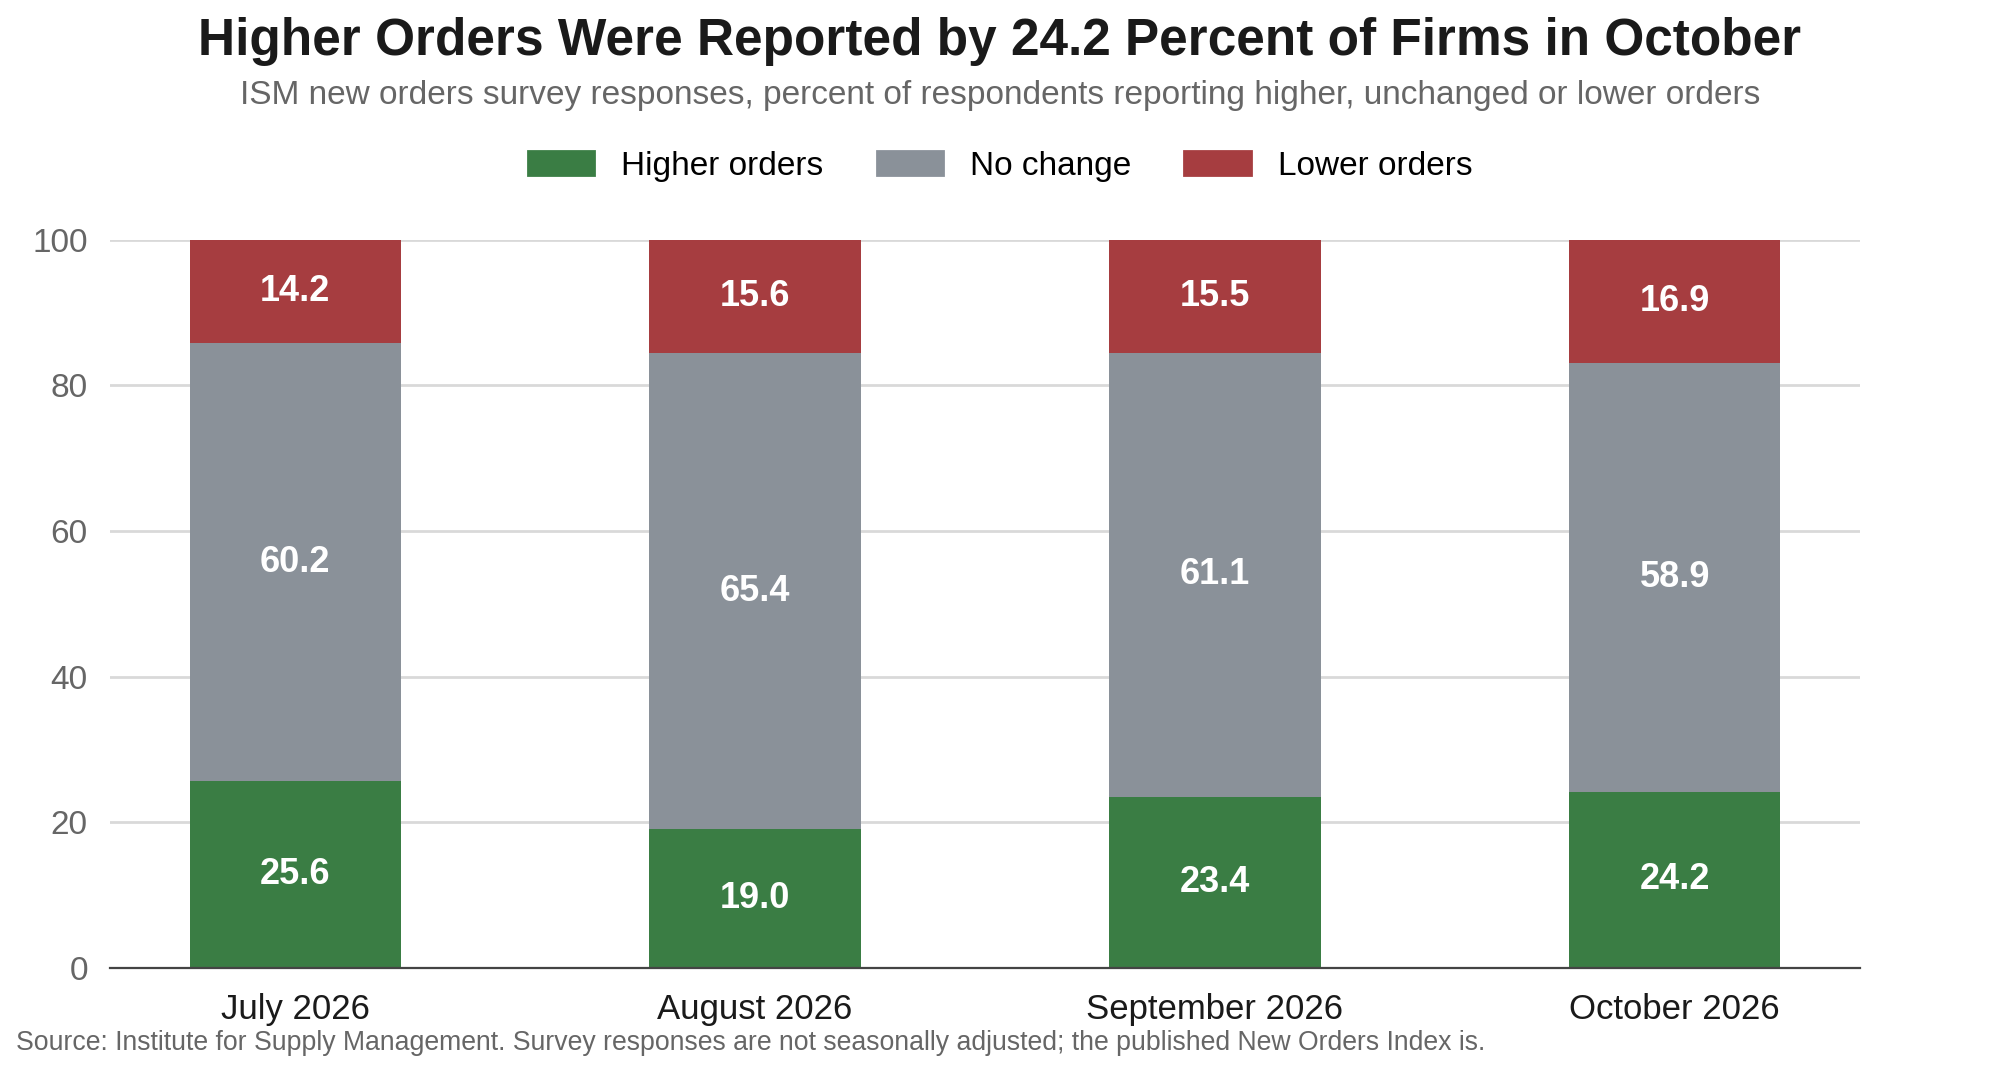
The raw responses show orders little changed. The share of panelists reporting higher orders edged up to 24.2 percent from 23.4 percent, but the share reporting lower orders rose by more, to 16.9 percent from 15.5 percent, and the no-change share fell to 58.9 percent from 61.1 percent. The gap between those reporting higher and lower orders narrowed to 7.3 points from 7.9. On the unadjusted responses the index slipped about 0.3 point to 53.7, so the published series’ 0.2-point gain reflects the seasonal factors.
Other demand measures were firmer. New export orders rose 0.3 point to 51.2 and imports rose 1.9 points to 52.9, both in expansion. Customers’ inventories were unchanged at 41.6, the 25th consecutive month judged too low, which has tended to come before restocking. Buyers extended the time they commit to production materials to 87 days from 84 and shortened maintenance and repair supplies to 46 days from 49, with capital expenditure lead times about unchanged at 175 days against 176 in September.
More Industries Are Growing, and That Supports Our 2027 Forecast
The strength in this survey is broader than the headline suggests, and that breadth is one of the key reasons our 2027 forecast is above consensus. We look for real GDP to grow 2.6 percent in 2027 on a full-year average basis, up from 2.3 percent in 2026, against a median of 2.2 percent in the Philadelphia Fed’s third-quarter Survey of Professional Forecasters, and for manufacturing output to rise 2.9 percent in 2027 after 1.7 percent this year. A PMI of 55.5 says that the factory sector is growing, but the count of industries says how many parts of it are participating, and the answer in October is more than in September.
Eleven of 18 industries reported growth in each of new orders, production and backlogs, up from 10 in September, and seven reported higher imports, up from four, which suggests more industries are buying inputs for production they expect to carry out. The number reporting higher employment was unchanged at eight, and the number reporting higher export orders fell to two from four, the one place where breadth narrowed. Production is running ahead of orders, 59.0 against 55.5, and with customers’ inventories judged too low for 25 months the gap is more likely to be filled by restocking than by a pullback in output. Our forecast has business inventories adding about 0.4 percentage point to real GDP growth in 2027 after subtracting about 0.1 point in 2026, and the October survey is consistent with that turn.
Hiring Is Steady, While Hours Have Run Ahead of It
The Employment Index slipped 0.3 point to 52.4 in October, a fourth month in expansion after 17 straight months below 50, although positive comments on hiring outnumbered negative ones 1.8 to 1, up from 1.5 to 1. ISM has said that readings above 50.3 usually go with rising manufacturing payrolls in the Bureau of Labor Statistics data, and October is the fourth reading in a row above that level.
The raw responses are better than the published index. Of the panelists, 14.4 percent reported more head counts, 10.8 percent reported fewer and 74.8 percent reported no change, so the net share adding head counts widened to 3.6 percentage points from 0.8 in September. The unadjusted Employment Index was about 51.8, against about 50.4 in September, so the 0.3-point decline in the published series reflects the seasonal factors. That reverses September, when most of the gain in the published index came from the adjustment, and it says hiring is improving by more than the headline shows.
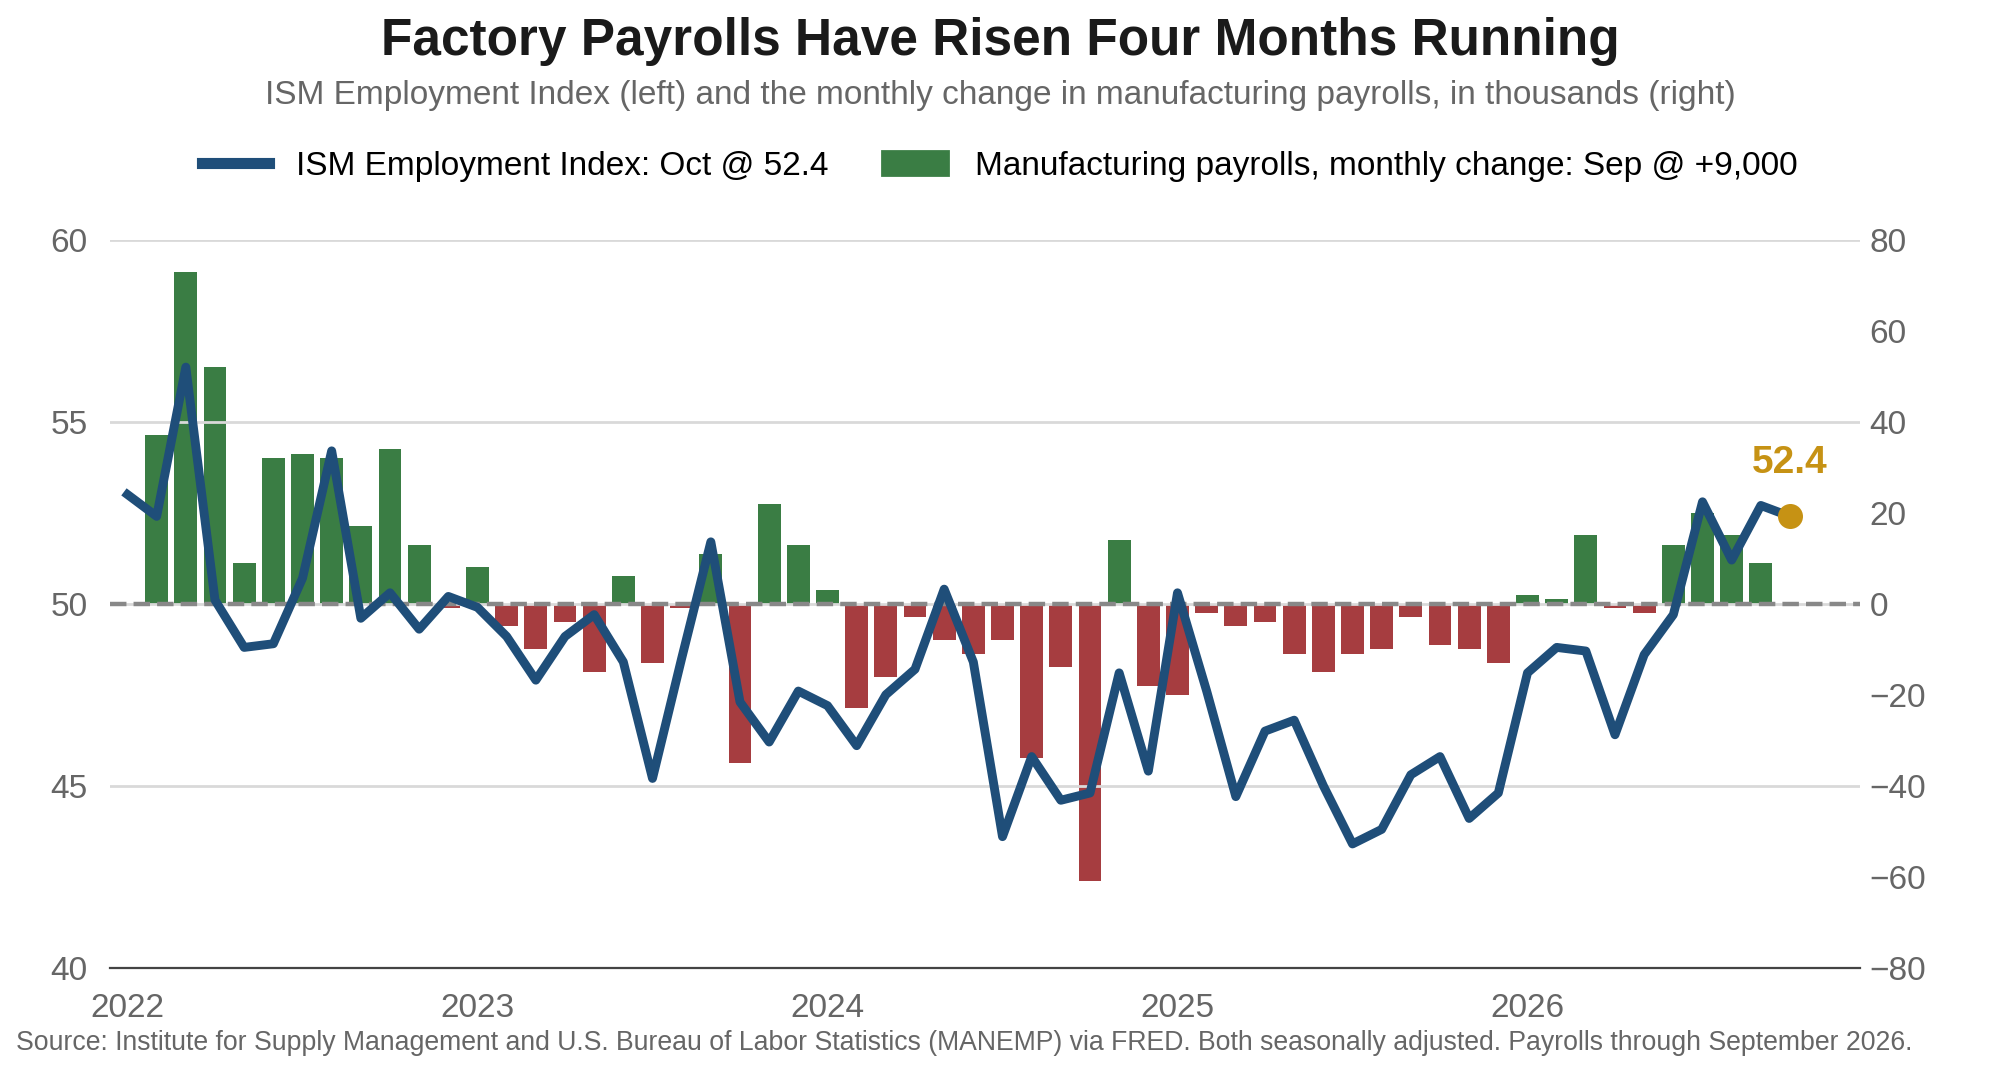
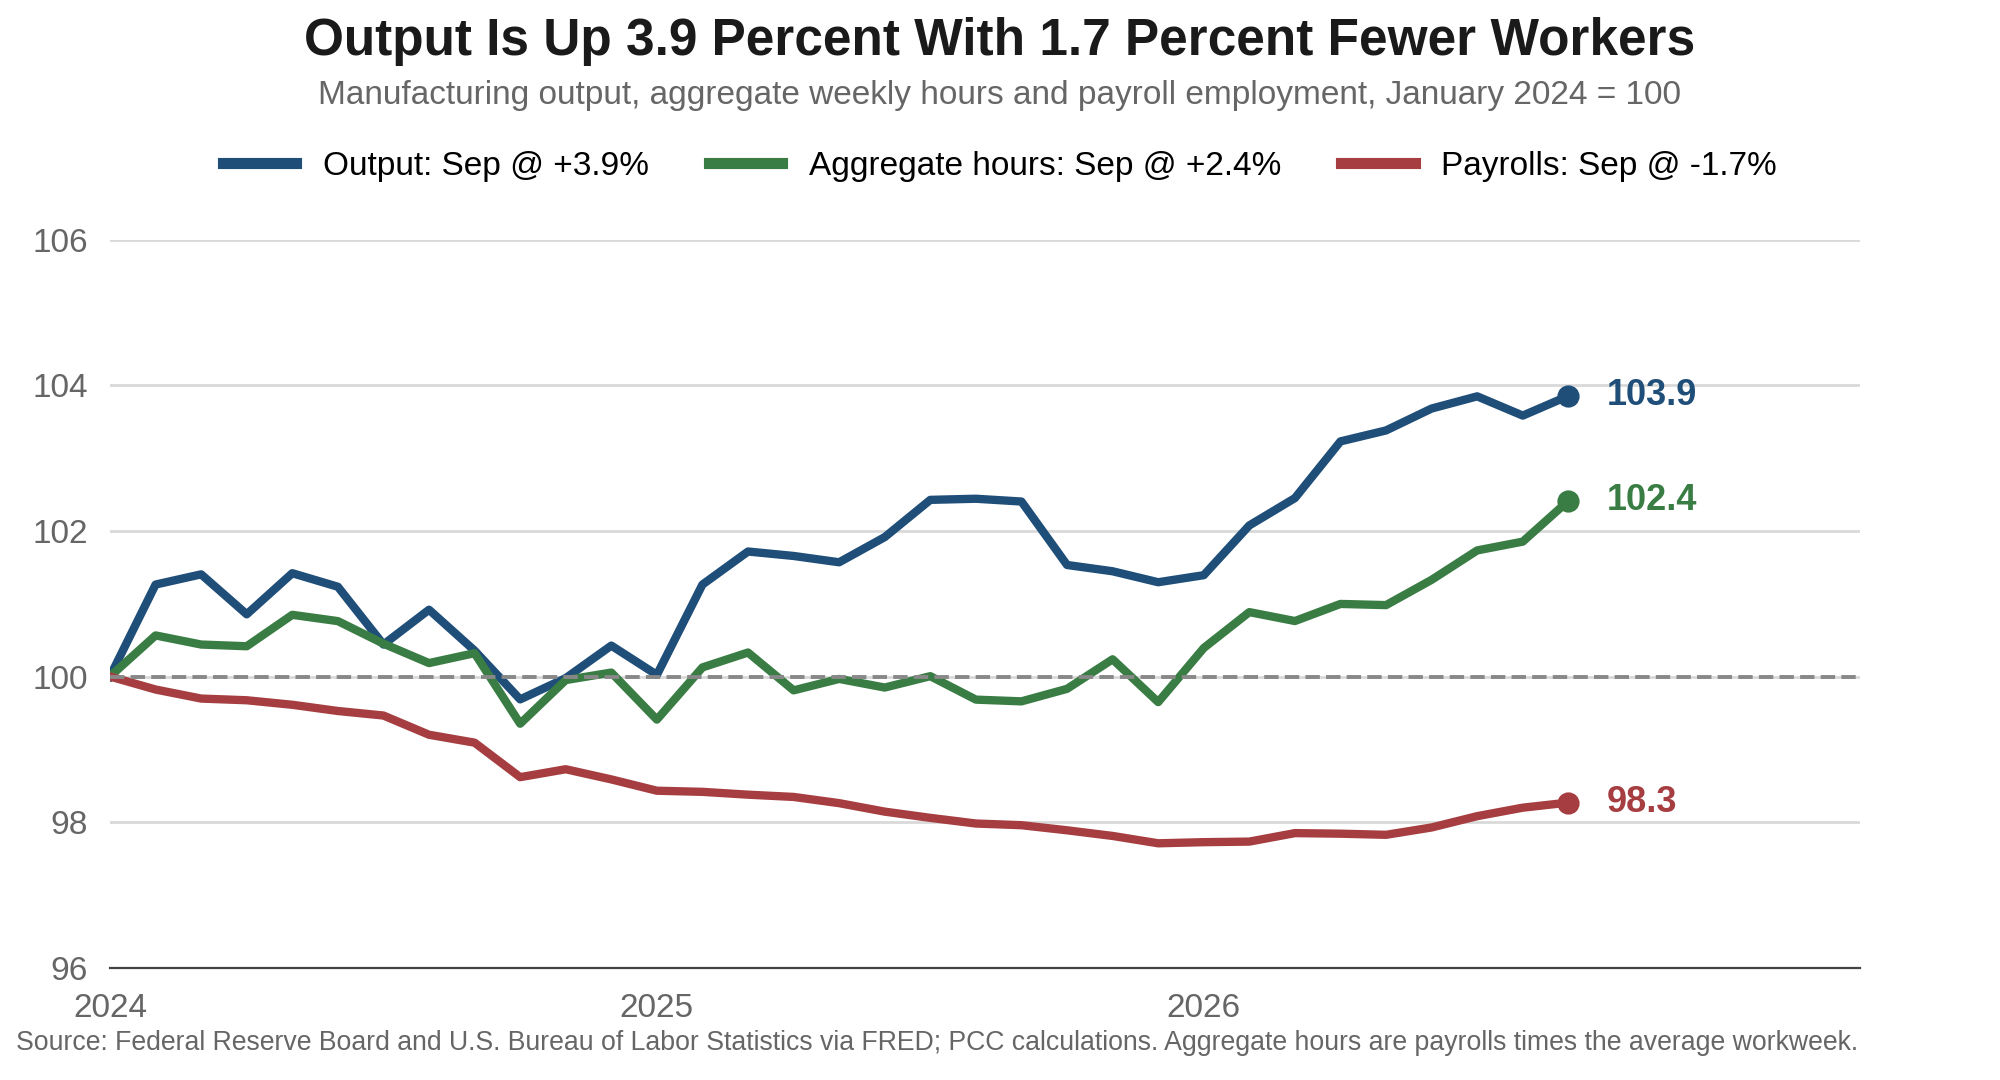
Payroll data are beginning to confirm the survey. Manufacturing payrolls added 9,000 jobs in September after 15,000 in August and 20,000 in July, following revisions, 44,000 over three months, and now stand 72,000 above December’s trough. Employment is 40,000 above a year earlier, while payrolls are still 1.7 percent below their January 2024 level, factory output is 3.9 percent above it and aggregate hours are 2.4 percent above it. The pace slowed in September, however, and Friday’s employment report will show whether hiring is keeping up with orders.
Hours are still running ahead of hiring. Average weekly hours in manufacturing rose to 42.0 in September, the highest since January 2019, from 41.8 in July and August. The 0.9-hour gain from December’s 41.1 equals roughly 275,000 workers at December’s workweek, while payrolls have added 72,000. Manufacturers lengthen the workweek first because it can be cut back quickly if orders fade, while a new hire is a commitment that takes months to unwind. Four straight gains in payrolls say some have started to commit, and the gap between hours and hiring is the room payrolls have to grow if orders hold.
Production Jumped, and the Investment Cycle Is Still Running
Core capital goods orders, meaning nondefense orders excluding aircraft, reached $88.0 billion in September, up 0.5 percent from August and 13.5 percent from a year earlier, and up 11.1 percent since December alone. The capital spending behind this recovery shows no sign of slowing, which fits the pattern of factory output rising faster than hours or payrolls since the start of 2024.
The Production Index jumped 2.3 points to 59.0, a 12th month of growth and the highest reading since November 2021, and more than half of it shows up before seasonal adjustment. On the raw responses 27.6 percent of panelists reported higher output and 11.5 percent reported lower, an unadjusted index of about 58.1 against about 56.8 in September, and production comments in the panel ran 2 to 1 positive. Industrial production points the same way, with manufacturing output rising 0.3 percent in September after a 0.3 percent decline in August and up 1.4 percent from a year earlier, and manufacturing capacity utilization at 75.9 percent in the Federal Reserve’s G.17 report.
Supplier deliveries slowed for an 11th consecutive month, at 59.1, up 0.1 point from September, and the Inventories Index rose 2.8 points to 51.4, about 50.7 on the unadjusted responses against 49.2 a month earlier. Longer delivery times can reflect firming demand or genuine scarcity, and with production rising both are likely at work. Electronic components have been in short supply for 20 consecutive months, electrical components for 16 and memory for 10, and lead times were cited in 41 percent of the negative panel comments, up from 21 percent in September, so scarcity is taking a larger share of the complaints.
Prices Eased in the Survey and Accelerated in the Data
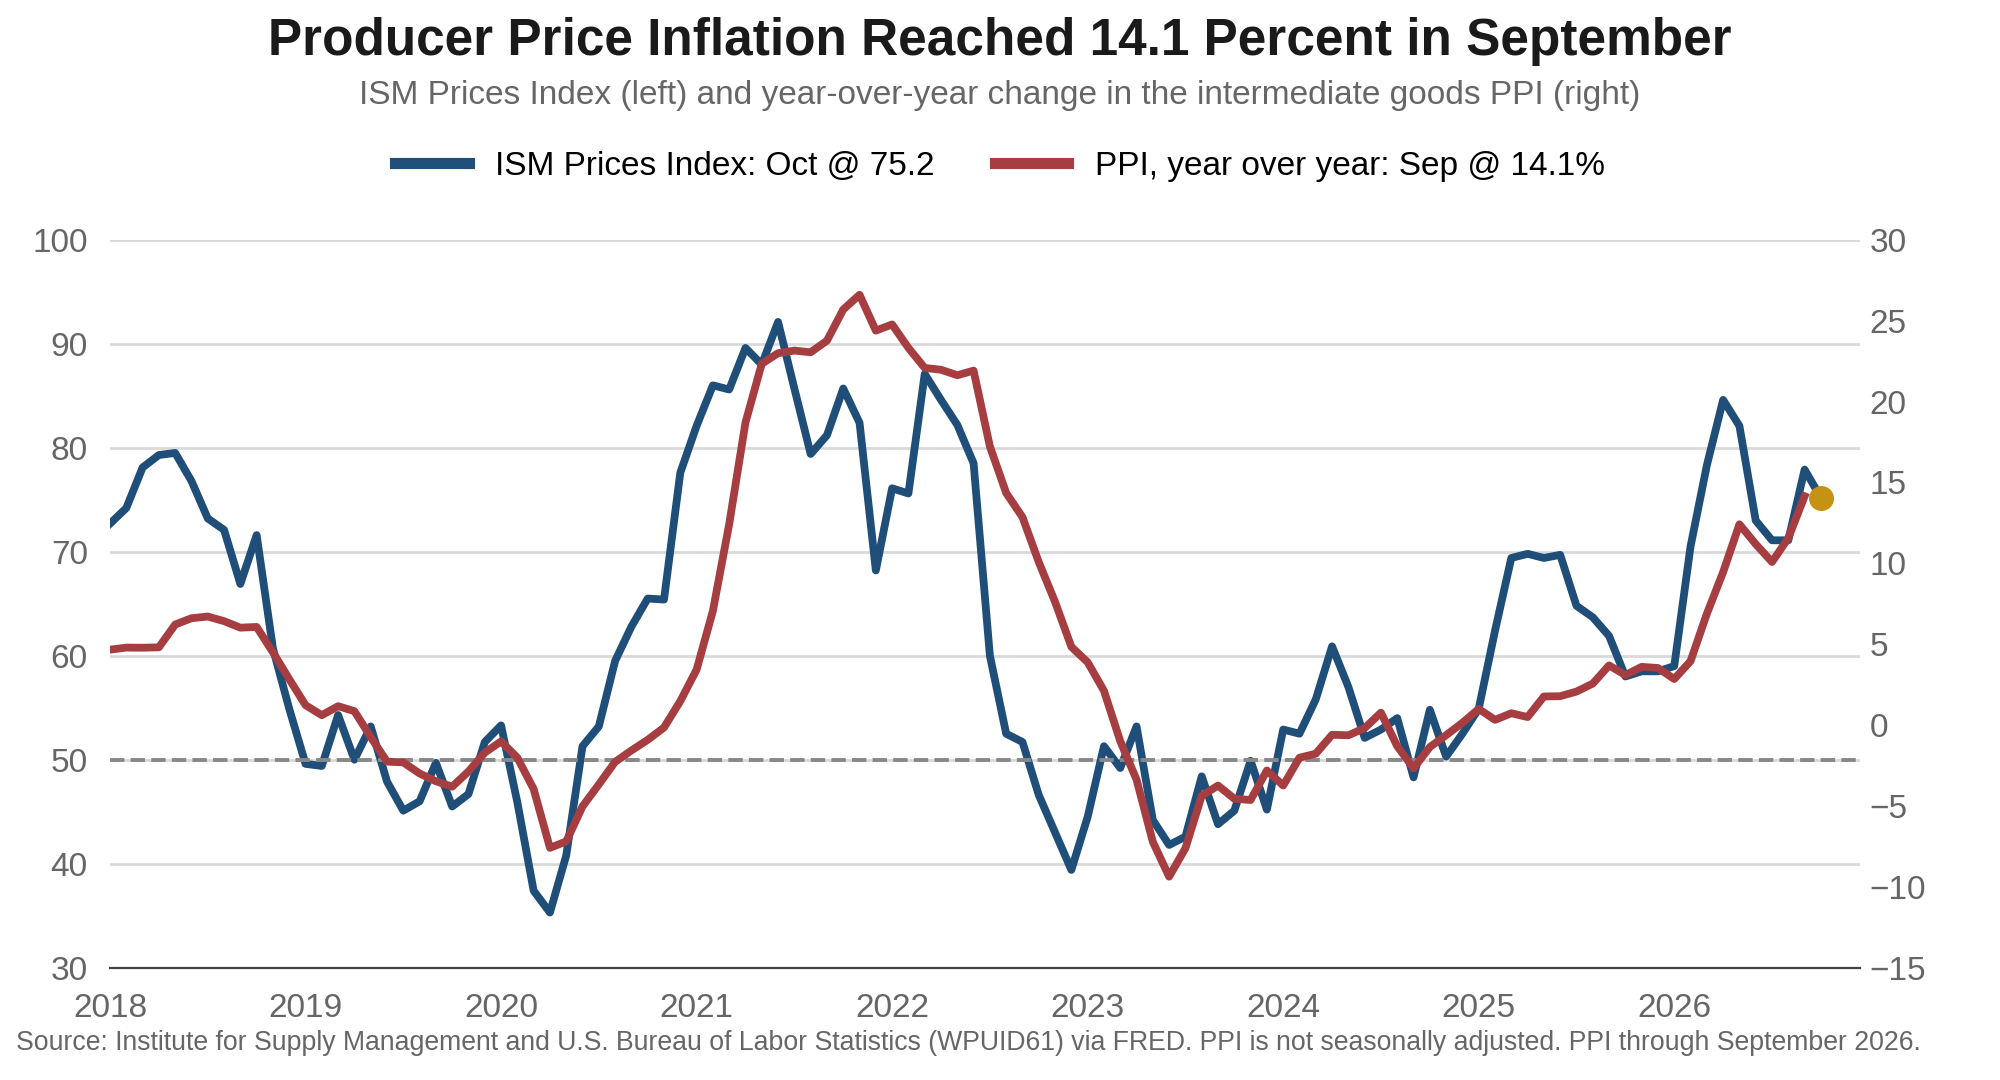
The Prices Index fell 2.7 points to 75.2 in October, but ISM’s panel has now reported rising input costs for 25 consecutive months, with aluminum higher for 35, copper for 16 and steel for 12. Pricing volatility led the complaints in the negative panel comments at 62 percent, up from 46 percent in September.
Fewer respondents paid higher prices, 53.1 percent against 58.6 percent, and the share paying lower prices was unchanged at 2.8 percent, so the net share paying more is 50.3 percentage points against 55.8 in September.
The official price data have accelerated. Producer prices for processed goods for intermediate demand, the closest official match for ISM’s Prices Index, rose 2.4 percent in September to 300.6, well above the 2022 peak of 283.1, and the increase from a year earlier reached 14.1 percent from 11.6 percent in August, the highest since August 2022. The survey eased in October while producer price inflation was accelerating, so the easing in the survey has not yet shown up in the price data.
Tariffs, the Iran war and shortages of the components the AI buildout is absorbing all appear in the panel comments, but their weights have shifted. Tariffs fell to 25 percent of the negative comments from 34 percent and the Iran war to 21 percent from 30 percent, while pricing volatility rose to 62 percent from 46 percent, which suggests the pressure is coming more from swings in cost and availability than from any single policy.
The Regional Surveys Were Mixed, and Orders Cooled
The Chicago Business Barometer, formerly the NAPM-Chicago, fell 3.5 points to 55.3 in October from 58.8, giving back less than a third of September’s 11.7-point jump. Employment jumped 10.3 points to its highest reading since April 2021, reversing September’s 4.3-point decline, and prices paid rose 8.9 points to their highest since December 2021. S&P Global’s final manufacturing PMI eased to 54.9 from 55.9, after a flash reading of 56.0, but is still well above 50.
The five regional Fed surveys were stronger on balance but cooler on orders. The mean of the five district headline indexes edged up to 13.8 from 13.4, the fourth consecutive reading at 13.4 or higher. Empire State rose to 25.5 from 7.6 and Dallas to 13.4 from 9.8, while Philadelphia fell to 20.9 from 37.8, Kansas City to 11 from 14, and Richmond was unchanged at a negative 2, its second negative reading in a row. Richmond’s survey also leans toward housing-related manufacturing such as furniture, home textiles and wood products, so the negative readings fit the weakness in residential construction, where housing starts fell 5.2 percent in September.
The soft spot is new orders. Philadelphia’s new orders index fell to 4.3 from 29.2, Kansas City’s to 3 from 24 and Dallas’s to 9.3 from 30.7, and the five-district average fell to about 6.4 from 16.0. Employment was a little softer as well, with the five-district average at 7.0 against 8.9 in September. The outlooks were split, with Dallas’s index of expected general business activity rising to 38.1 from 20.8 and Philadelphia’s future activity index falling to 33.0 from 52.9. A five-district average of 13.8 is consistent with a PMI above 50, which is where the national survey sits, but the cooling in orders is a reason to wait for November’s readings before reading too much into October’s.
Our Call
Manufacturing is strengthening more broadly, and that is one of the key reasons our 2027 forecast is above consensus. Production is at its highest since November 2021, all five components of the PMI are in expansion, 11 industries report growth in orders, output and backlogs, and customers’ inventories are still too low. That is the footing under our forecast, and we look for manufacturing output to rise 2.9 percent next year with restocking and capital spending doing much of the work. Because hiring follows orders by several months, we expect manufacturing payrolls to keep rising modestly into early 2027 while the Manufacturing PMI holds in the mid 50s.
The unadjusted readings are better than the published ones for hiring and worse for orders and production. On the unadjusted responses new orders slipped to about 53.7, production gained 1.3 points rather than 2.3 and employment rose 1.4 points rather than falling 0.3. Regional new orders cooled sharply, export orders are narrowing and the share of manufacturing GDP in contraction rose to 6 percent from 2 percent. The recovery is still led by capital goods, with core orders up 13.5 percent from a year ago, so a pause in capital spending is the main thing that could slow it.
The October dissents and the October ISM survey both point toward the December increase we expect. The Committee left the target range at 3.75 to 4.00 percent, as we anticipated, with two dissents in favor of a quarter-point increase, and the advance estimate then showed third-quarter real GDP growing 3.4 percent at an annual rate. We continue to look for an increase on December 9 to 4.00 to 4.25 percent and another in March to 4.25 to 4.50 percent, with June still an even call and a third increase possible if inflation does not ease. That call is ceteris paribus, and we also expect long-term rates to stay near 5 percent through 2027 as manufacturing strengthens and restocking begins. Friday’s employment report and October’s consumer price index on November 10 are the releases most likely to settle the timing.
Two things would break the call. The first is a reversal in orders. If November’s ISM New Orders Index and the regional new orders indexes both give back October’s level, the order book will look like it has been moving sideways near 55 instead of building, and we would trim our 2027 manufacturing forecast and lose confidence in the December increase. The second is a retreat in the technology capital spending behind the component shortages, which would remove the demand keeping supplier deliveries slow and the restocking we expect to follow.
Mark P. Vitner – Chief Economist, Piedmont Crescent Capital
mark.vitner@piedmontcrescentcapital.com · (704) 458-4000
Disclaimer: This report is provided for informational purposes only and does not constitute investment, legal, tax, or accounting advice, nor an offer or solicitation to buy or sell any security. Information is drawn from sources believed to be reliable, including the Institute for Supply Management, the U.S. Bureau of Labor Statistics, the U.S. Census Bureau and the Federal Reserve Board, but its accuracy and completeness are not guaranteed. Views expressed are those of the author as of the date of publication and are subject to change without notice. Past performance is not indicative of future results.